All the charts and data we refer to can be found on the Yacht Club page.
Hey everyone,
We usually try to keep things simple when the market is moving quickly, since it all demands a bit more attention, and a bit more clarity of thought.
However, one note before we get into it: Many of you, dear readers, have created automated processes to download the Yacht Club PDFs. These processes involve logging in, creating sessions, and navigating a web-page with a script. This is complex. We do not want this process to be complex.
As such—by next weekend, we will update the API so that you can retrieve PDFs through the usual API endpoints. That will make this process much easier.
Thank you for your attention in this matter.
* * *
Last weekend, we sampled the data and looked for historical analogs.
Across more than twenty years of sampling for those situations nearest the current data setup, we find a mix of commodities rallying, inflation fears, Fed emergency cuts, and moments of geopolitical turmoil. And if we had to characterize what we see in those histories, it would be...
This is the bottom... for maybe a couple weeks.
Perhaps this is a triumph for our pattern-matching brains, that we already saw "unresolved tension" in the plot of the S&P 500. That this is not really a dip to buy sincerely, nor a trend to follow, but rather, a moment for a temporary stability.
We saw a "moment for temporary stability," and then new lows incoming.
Frankly, we thought that, this weekend, we'd be talking about how we should prepare for fresh downside—but it turns out that the market was impatient, and it beat us to the punch.
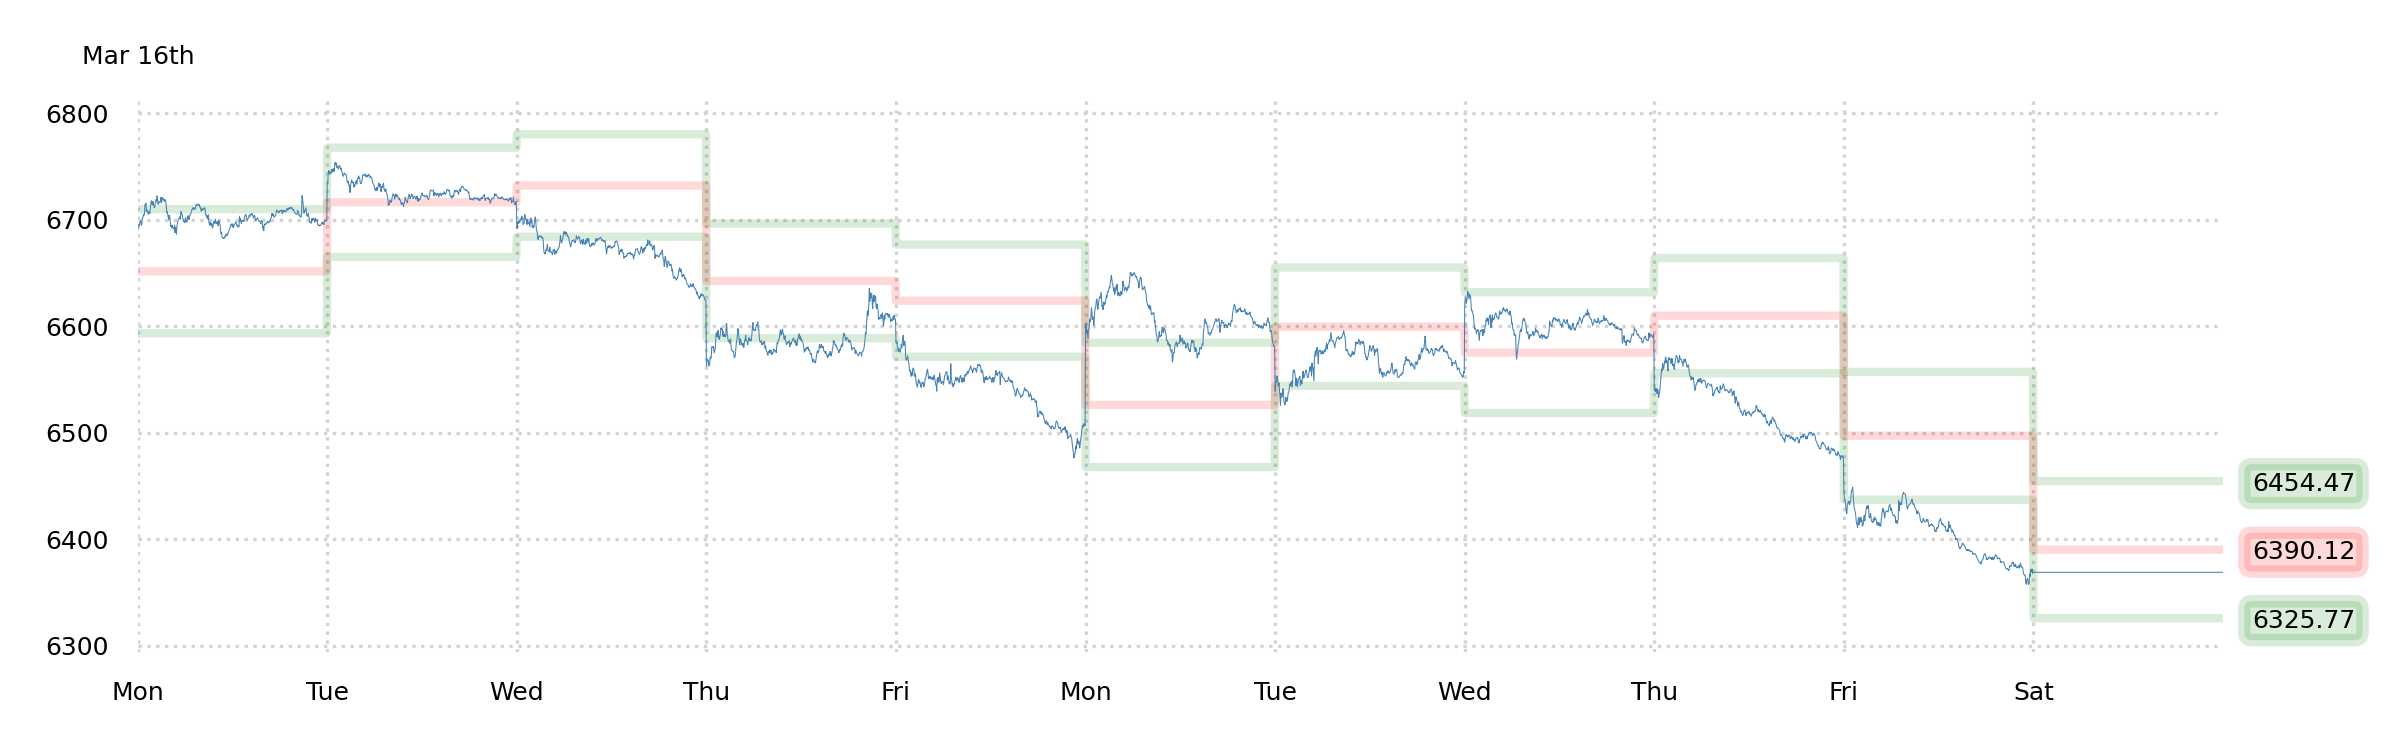
Friday plumbed those new depths. Judging by the composition of the GEX+ curve on Friday morning, we
thought that there would be a "relatively fast move down to 6400." That was indeed accomplished, and more.
But... now what?
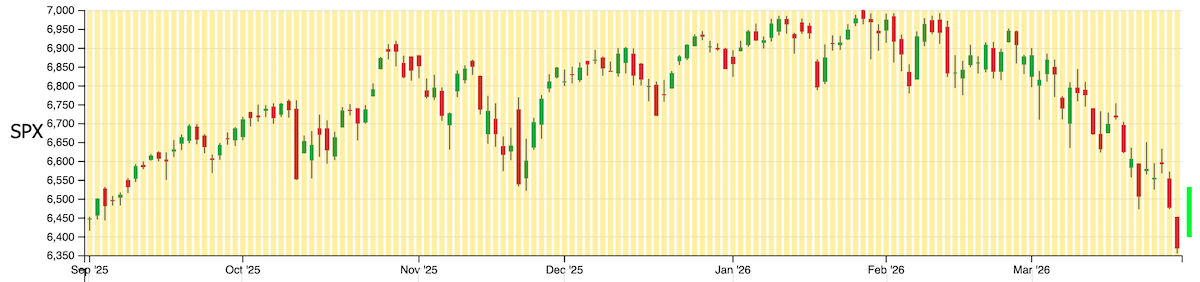
Before we consult the PDFs and Robot Jim, let's bring our own sophistry to the table: The chart looks like a prime candidate for a bear-market bounce.
This isn't entirely a subjective assertion. Our perverse desire last weekend was that the "moment for temporary stability" would last long enough to burn some extant put hedges (including those expiring at EOQ on Tuesday) and to raise RISC a bit (by lowering IV a touch and raising RV with some sideways-to-upside chop). This would allocate much more "potential energy" to the awaited next leg down.
Sadly, this did not transpire. Inevitably, the selloff that we got on Friday was a half-baked version of what we were waiting for, a toe just dipped in the water. As such, we think the "potential energy" has been mostly spent already. The natural path of least resistance here seems to be up. Consider also that the JPM Collar, whose put strike is up at 6475, is extremely well-telegraphed, and it would be easy to justify another game of
"Pop the Collar" by rising to, and perhaps even attempting to pin, that slippery strike.
If the above is classic "tactical" commentary, what's the "strategic" situation?
The market wants more war! There's a bit of a narrative inversion underway right now: Up until this point, the "war" has been a bad thing. But strictly speaking, war is never bad per se (see SPX between '03 and '07)—what's bad is that the global supply chain for energy is dramatically disrupted right now. As such, what the market "wants" is actually more war. A full commitment to ease the supply chain disruption! A freedom of navigation exercise! Boots on the ground!
So if, in the increasingly likely scenario that troops are committed to the region, you're tempted to to think, "what was already bad is getting worse"—don't! The market does not have scruples about such things, and a commitment to get more involved in Iran is actually a positive to the market right now (so far, all announcements have been very noncommittal).
So...
Tactically: Bounce likely, ceteris paribus.
Strategically: Firm escalation is actually a good thing, and escalation is likely.
Taken together, it's bullish. At least in the short term.
What about the data? Does it disagree?
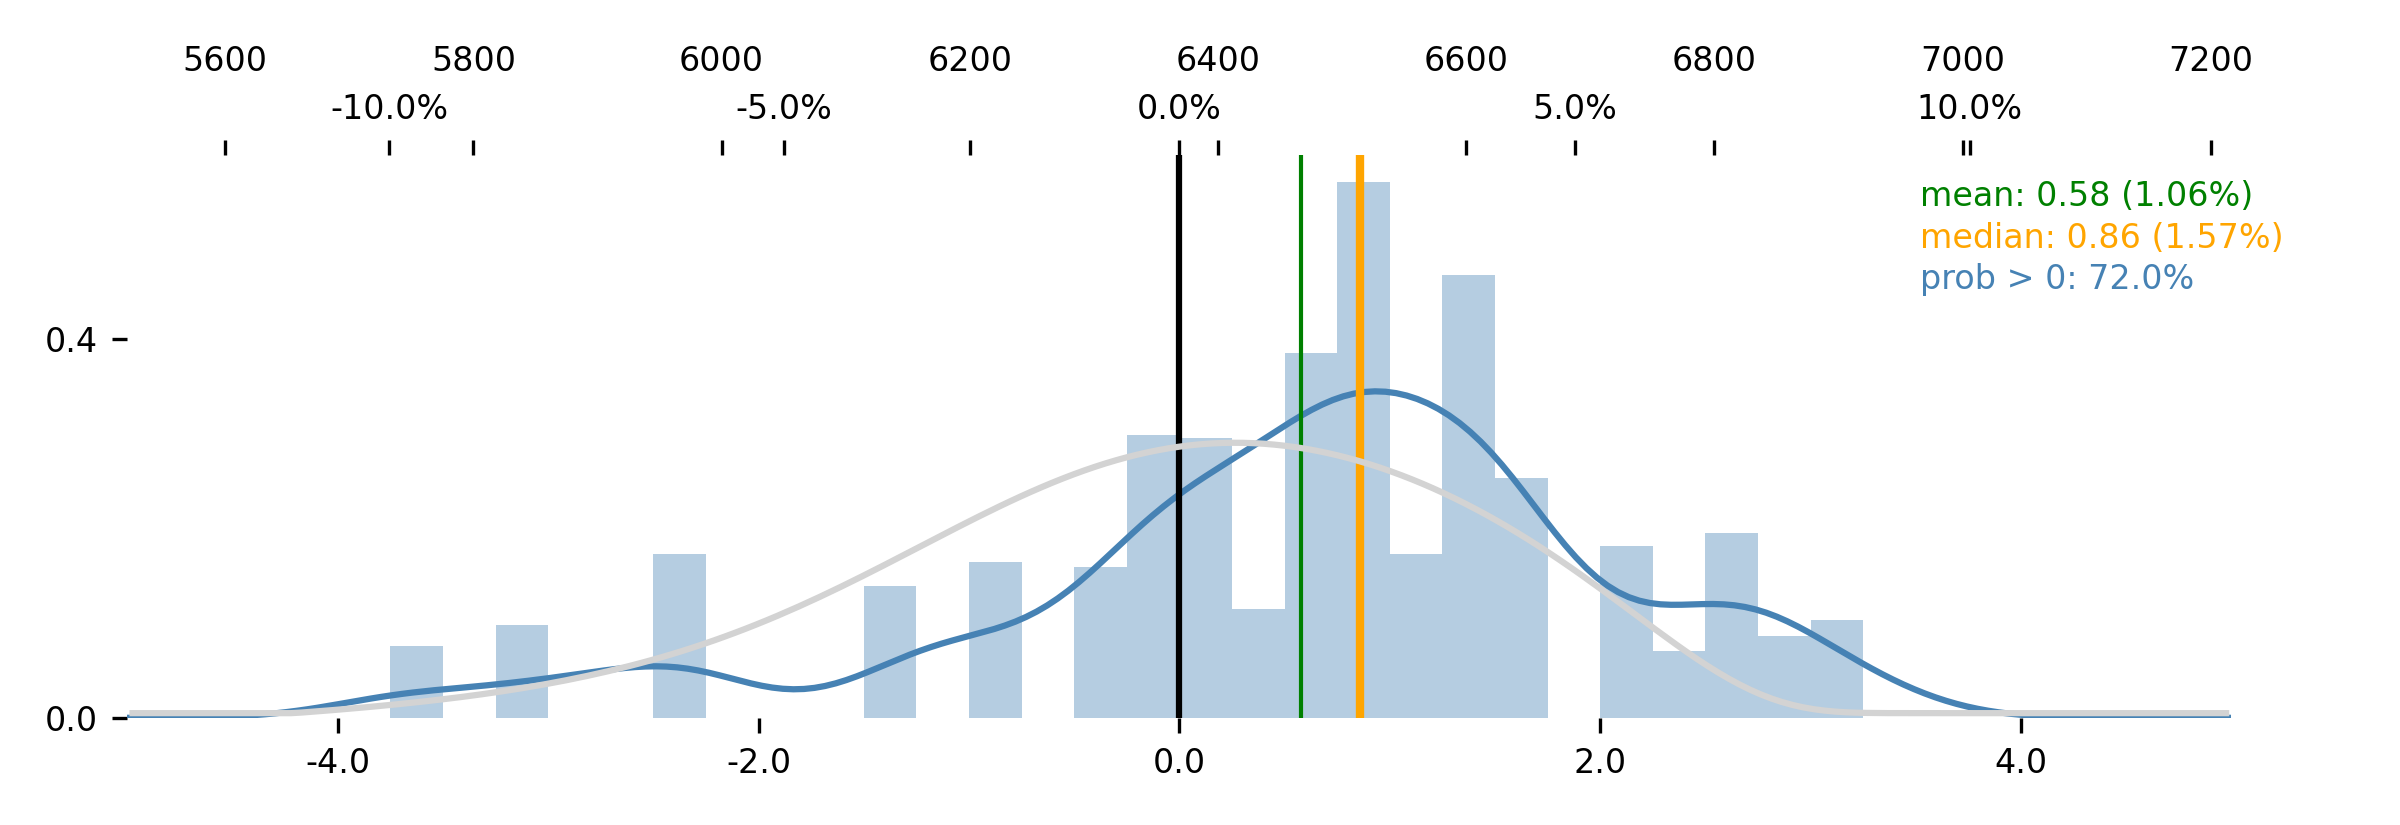
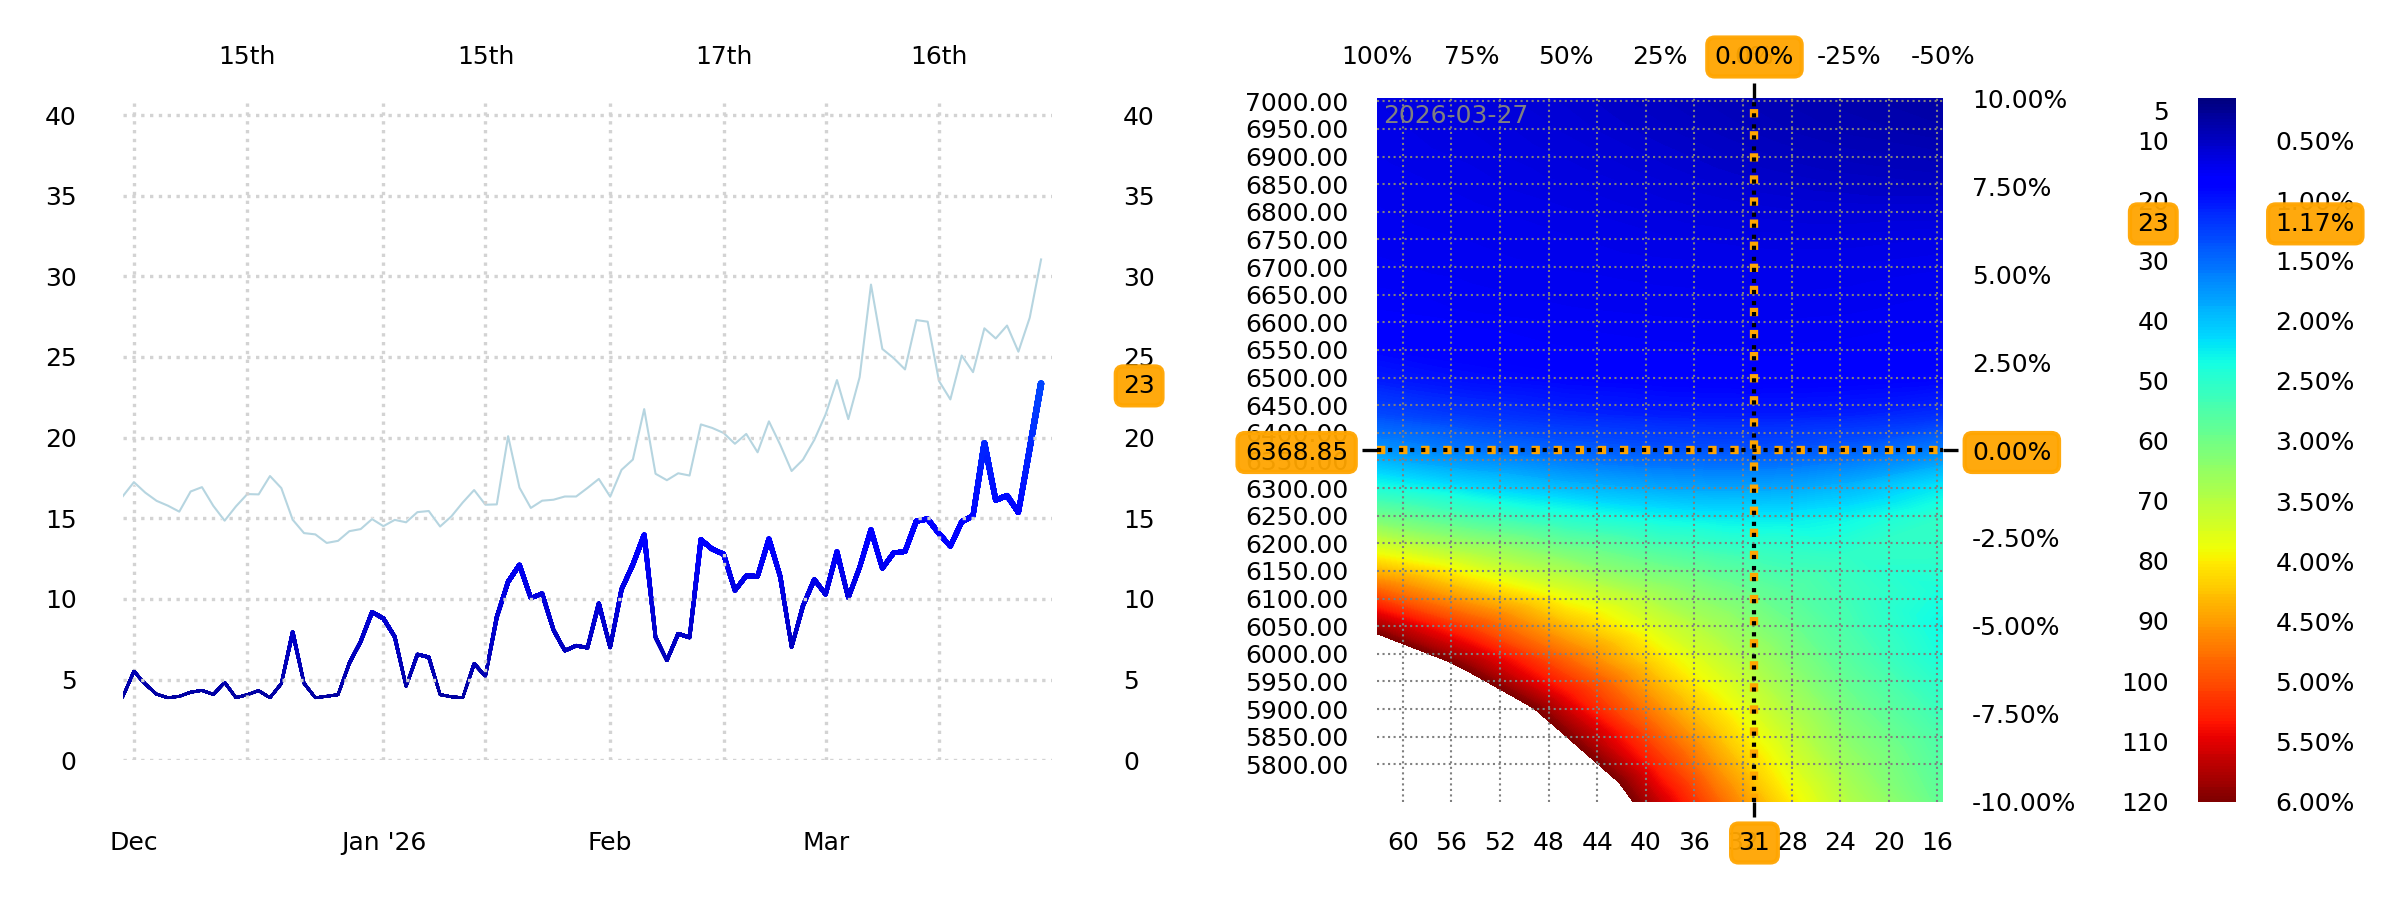
Jim does not equivocate. A mean 1-week gain of 1.06% and a probability of upside of 72%. However, to temper your excitement, the tail is present. A whopping ten percent decline is officially on the map.
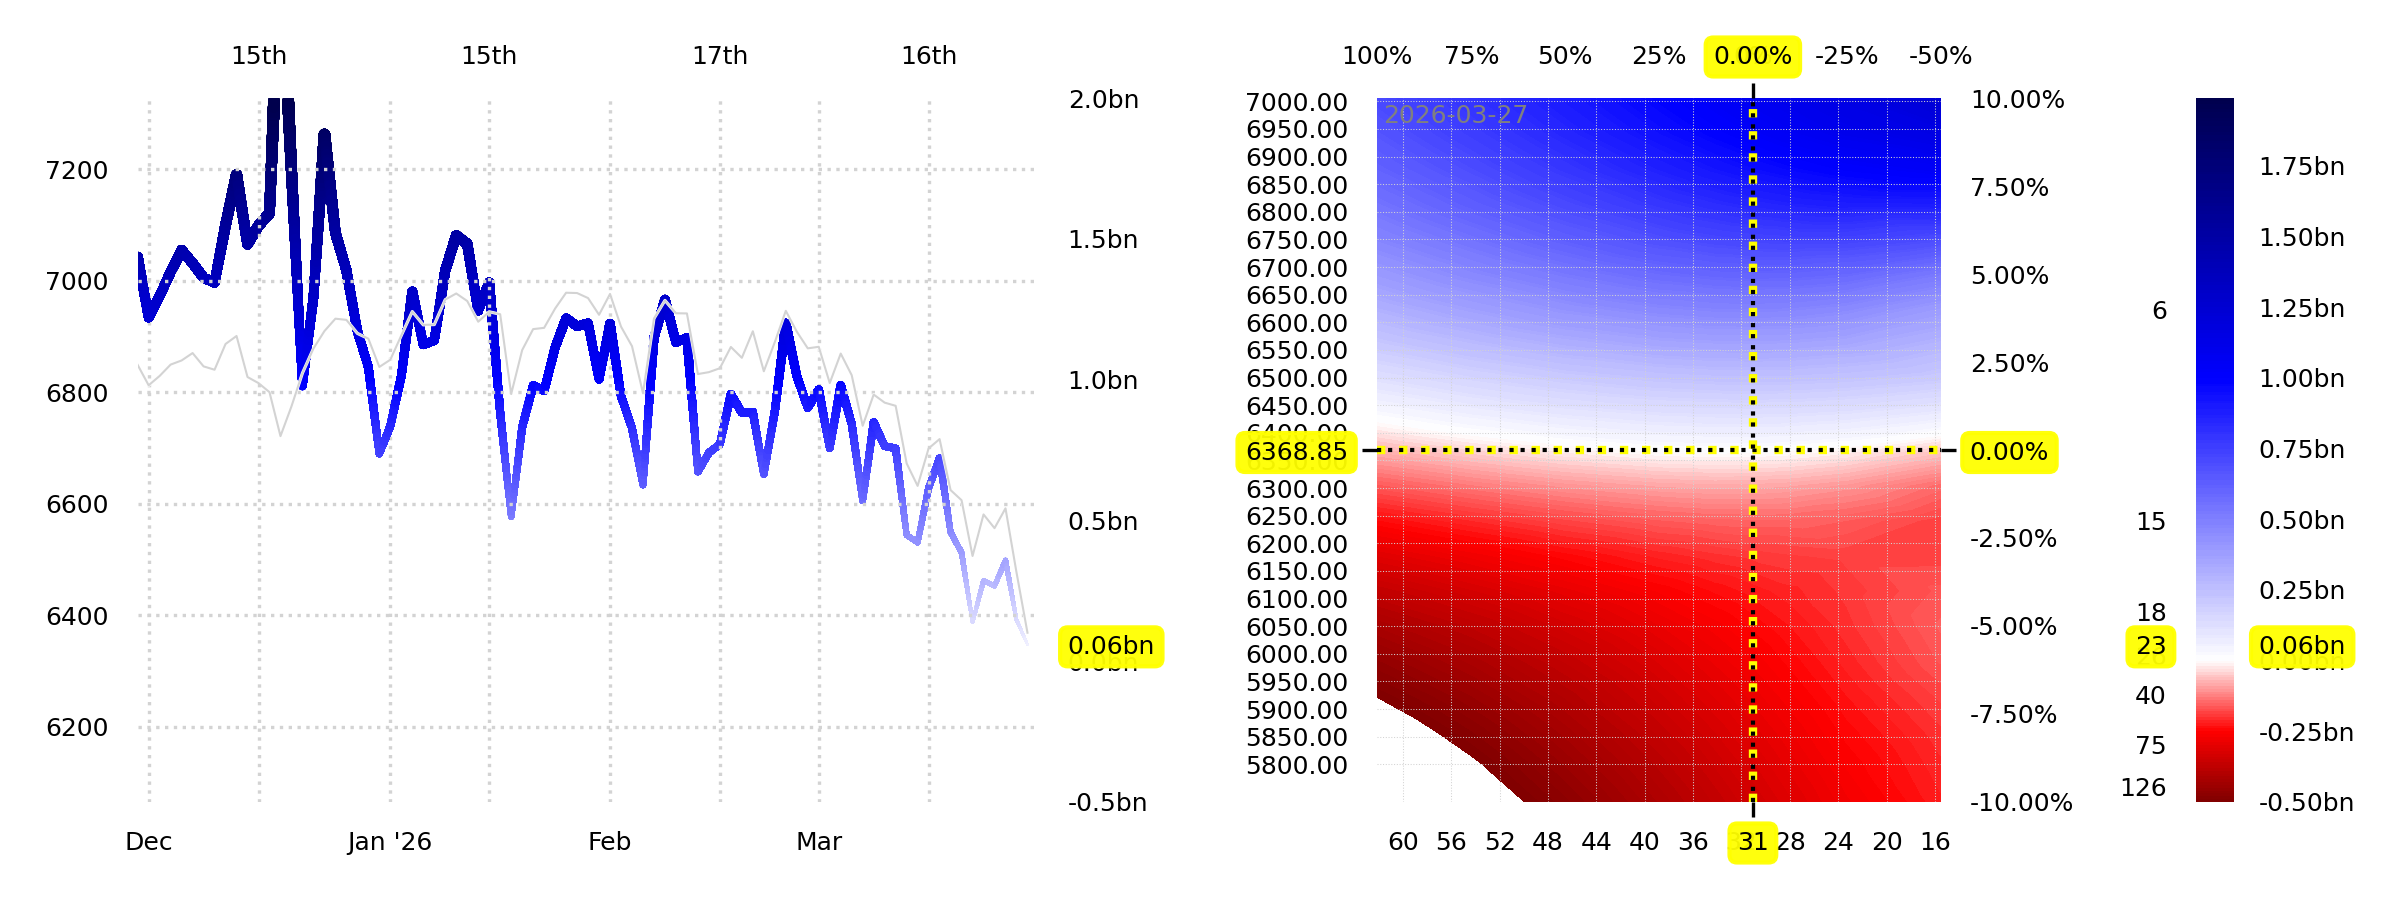
And it should come as no surprise that these big, scary moves are in range, because we're on the edge of "real volatility" right now.
Every downtick sucks liquidity out of the index. Every downtick has dealers taking incrementally, and then exponentially, more liquidity to hedge short gamma. We're right on the edge of that self-sustaining vol.
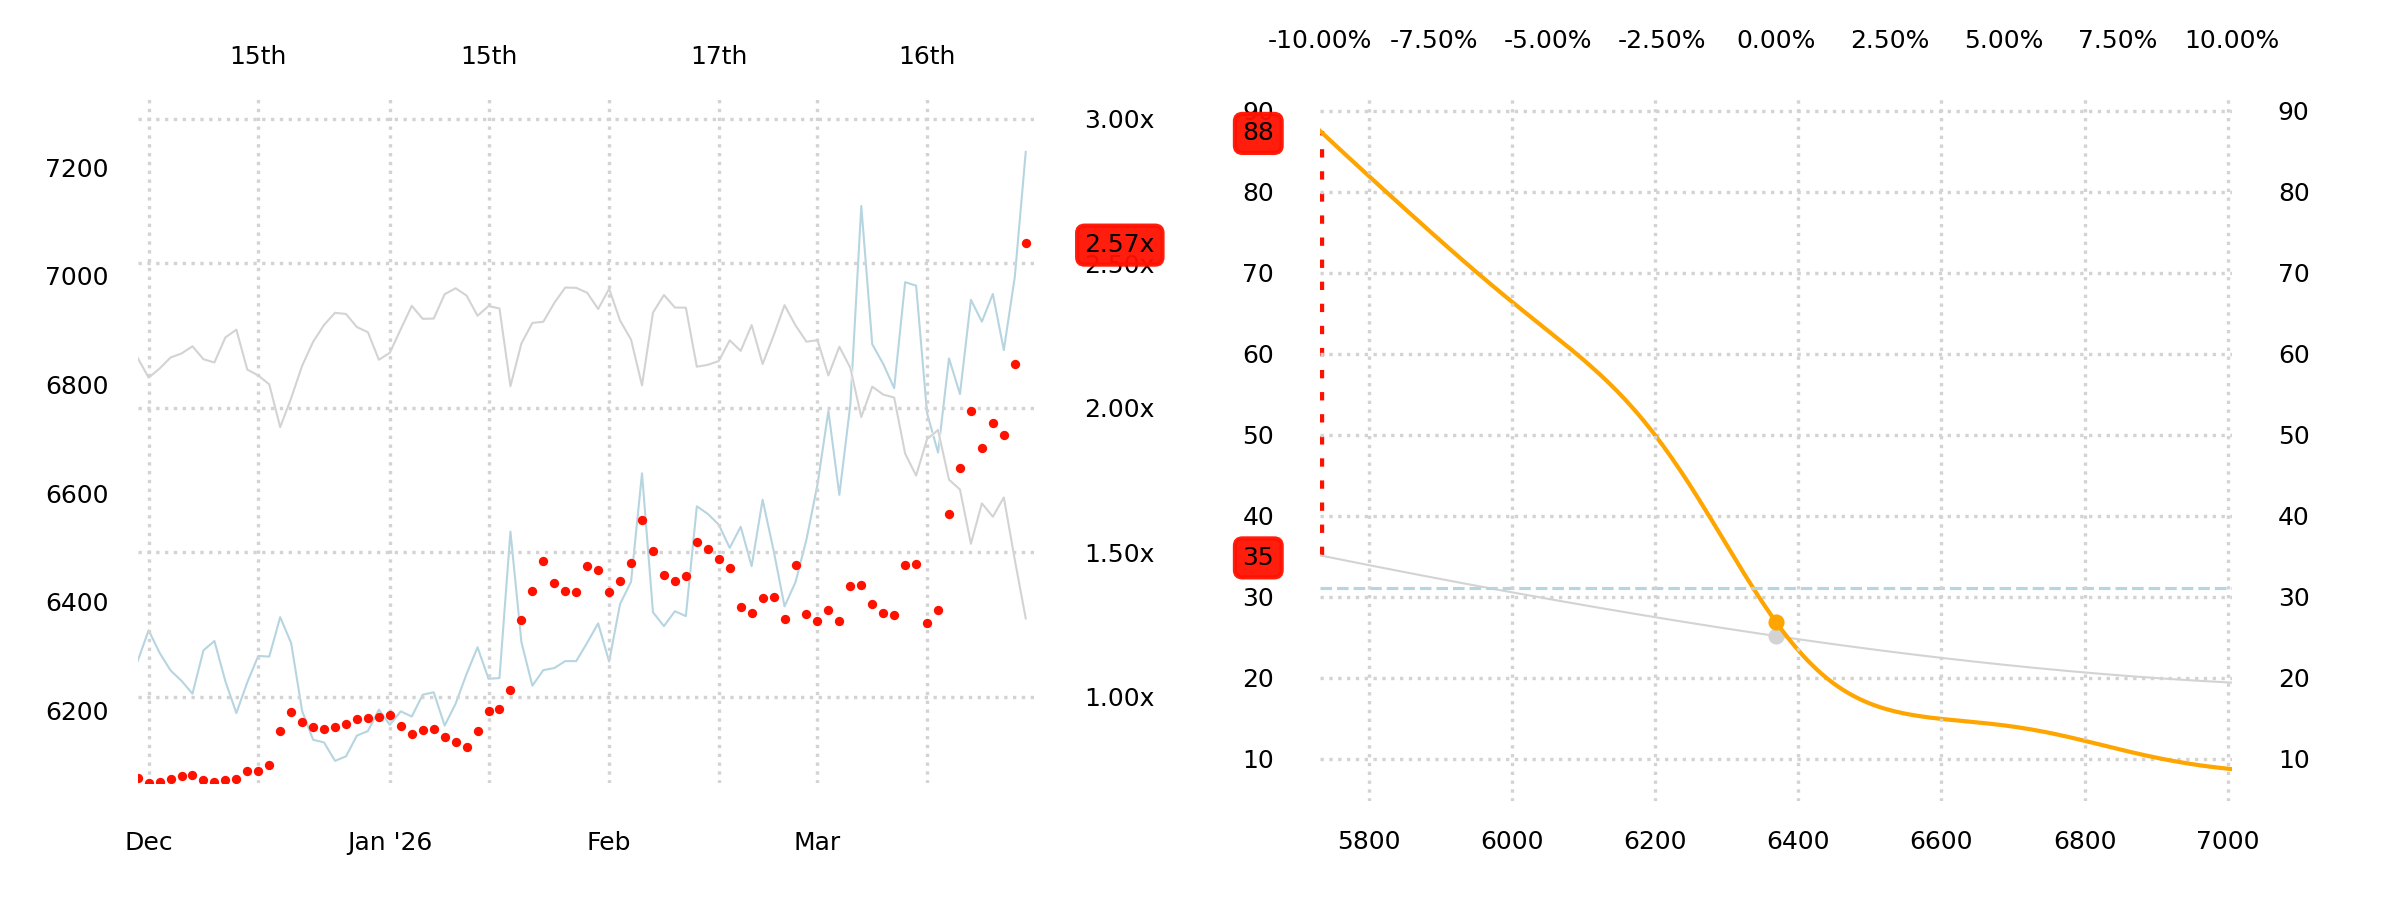
But we can't post these beautiful tropical heatmaps without the attendant "GIV-IV skew" and the "Crash Risk" multiple.
Crash Risk is at 2.57x. Several years ago, we'd have considered this a "normal" reading. It's not inherently concerning at all (our "guide" says above 3.00x is perhaps concerning). The better framing is that Crash Risk has been absurdly low for many years now, and that this is more akin to a normalization.
So, the basic idea is that, with the 90% (~5750) 1-month SPX put at 35 vols, there's really no future liquidity scenario that the market stumbles over itself to adjust to. Thus, we don't think it's likely that we see a liquidity-taking cascade into the limit-down abyss (though we hear many people proposing this right now).
Even if liquidity does get worse as GEX+ turns negative, "capital-R Risk" doesn't arise. People aren't "offsides." Liquidity isn't priced incorrectly.
Overall, we'd say that this is a strong case for a "bear market bounce."
Psychological note: You may be frustrated by any number of things right now. For instance, we are very much frustrated that the market didn't wait a couple extra days to find new lows, because we thought we had a really good idea of the likeliest path (a second leg down, after a short wait), and since the train left the station without us, we're kinda annoyed. This annoyance, this frustration, is what leads an individual to overtrade, or to "revenge" trade. We still want that short setup that was taken away from us, so we're very eager for an opportunity to short SPX, but that eagerness will easily get us into a bad trade. So here's your reminder not to do that. The market is a mystical mirror to your weaknesses. It peers into your soul and it finds your fragility and turns your vanities against you. You must cultivate no such weakness that can be exploited. Do you know what strengthens your defenses against these psychological infirmities? Long walks.
Good luck.
Enjoy the week!
The SqueezeMetrics Team