All the charts and data we refer to can be found on the Yacht Club page.
Hey everyone,
We didn't lose money this week, which is a nice counterpoint to last week. Long vol trades (long OTM calls/puts) broke even (we had one OTM put perform pretty well), and E-mini trading went very well—credit to that 0DTE dealer hedging data.
Speaking of that data, we only want to address one item this week: We've been getting the Yacht Club data up early for a couple days now, and at the moment, it looks like we can keep doing that.
This means that all of the "7:00am" data should now be available at more like 1:00am!
Wow. Now that is exciting.
But first...
- What... happened?
- The Return of Big DIX
- Pajama traders rejoice
What... happened?
We can't even remember what went on this week. Every day felt the same. We took no positions aside from intraday, and our intraday positions were almost entirely informed by 0DTE dealer re-hedging needs.
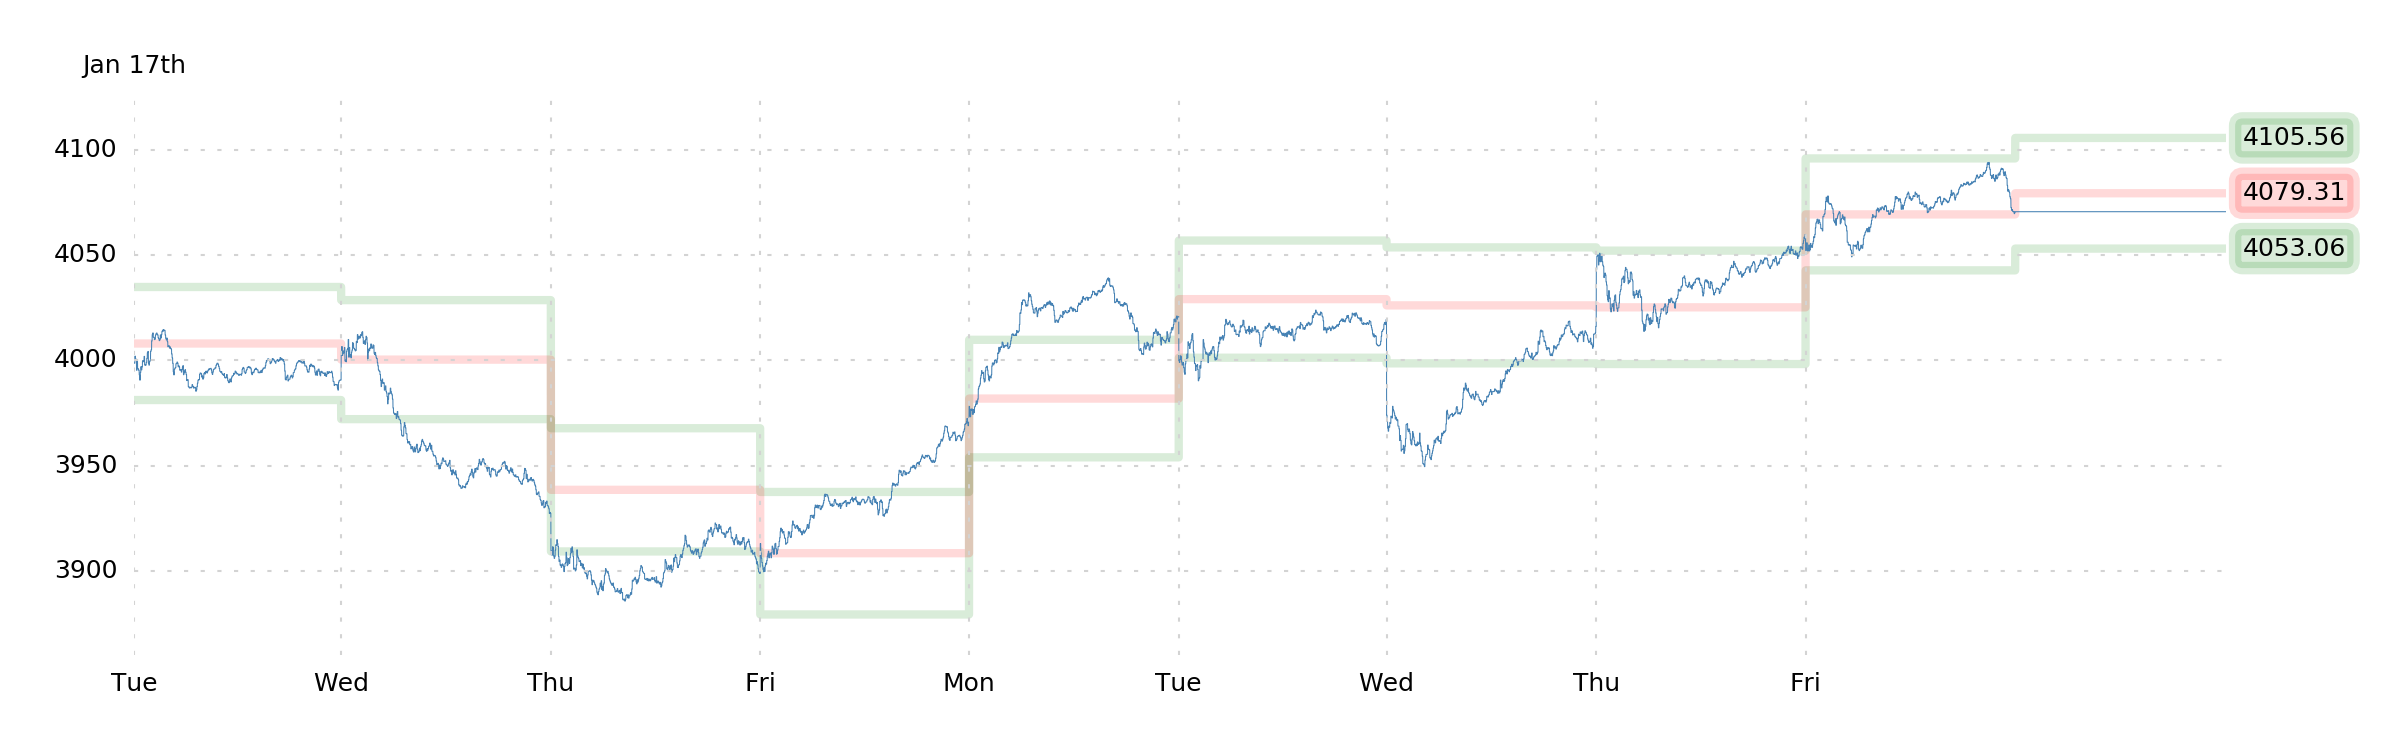
Apparently, the index went up:
Looking back at last weekend's note, despite feeling that we had no edge, we were expecting more "bear market dynamics," if anything. So this rally is interesting to us (especially in its persistence on Thursday and Friday!), and with no other explanation, we're inclined to believe that it was driven by "real money flows." Like, people actually, deliberately buying stocks.
Bolstering this thesis is
DIX, which has now printed above 50% for
eight straight trading days. That's a ton of buying, and it's something that hasn't happened since early June.
It is, of course, worth noting that the index did not subsequently go up in June after that buying—so you'd be right in eyeing this data with suspicion. Yes indeed, this data represents a ton of raw dollar flows into the S&P 500—but, really, the ground does not appear "fertile" for risk-taking right now.
There are a number of reasons to be skeptical of this little burst of bullish energy. Let's weigh them all.
The Return of Big DIX
First of all, these extreme readings of DIX are not actually associated with positive 1-month returns. So there's that.
Other things you'd probably want to see to be actually bullish:
- Put-buying: You want NPD to be -5 to -10, indicating at least "normal" levels of protective put-buying. Friday's NPD was +2.85, and the average NPD lately is around zero. That's not bullish at all.
- Risk premium / VIX: You want to see 30-day IVs (as measured by VIX) at least 20% more expensive than historical/realized volatility. It's something like 9%, which means that vol is on the "cheap" side, and there is no risk premium here.
- VIBE: You want to see VIBE near 20, indicating that VIX futures have been "covering" for the relative moves in SPX, and that meta-liquidity is priced well. It's 48, which is very boring with a little left tail.
- VGR: You want to see VGR between -10 and -20, which is where customers have the "safest" positioning with respect to vanna risk. VGR is -4.66. This is "neutral," and moving toward the bearish side of things. In 2022, this is where the market often turned over (customer option positioning matters a lot in this market).
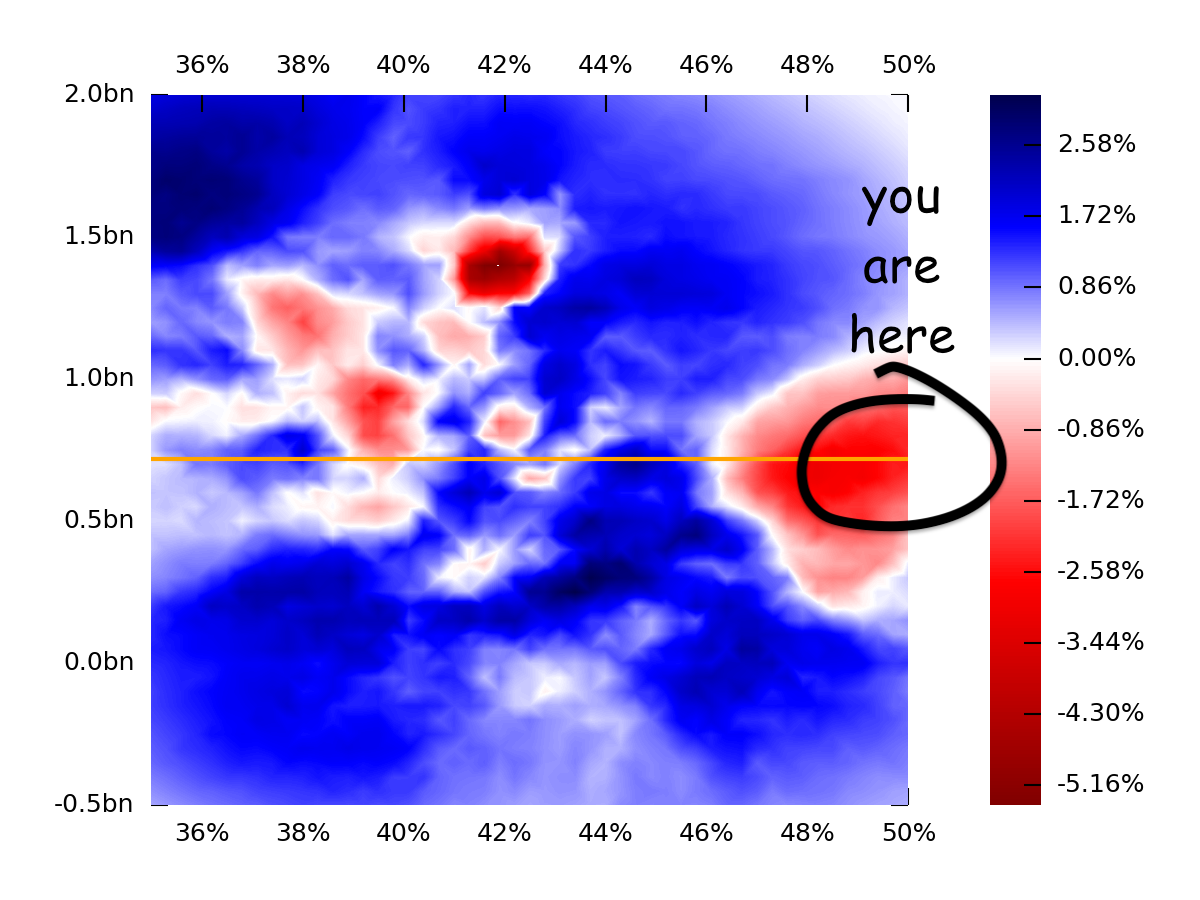
- GEX+: You want to see the possibility of liquidity improving on the way up. I.e., you want to see GEX+ rising as spot rises, so that price continually gets "stuck" at new, higher prices. But if you look at the GEX+ heatmap or the GIV-IV skew (orange line), you'll see that liquidity does not improve as SPX rises.
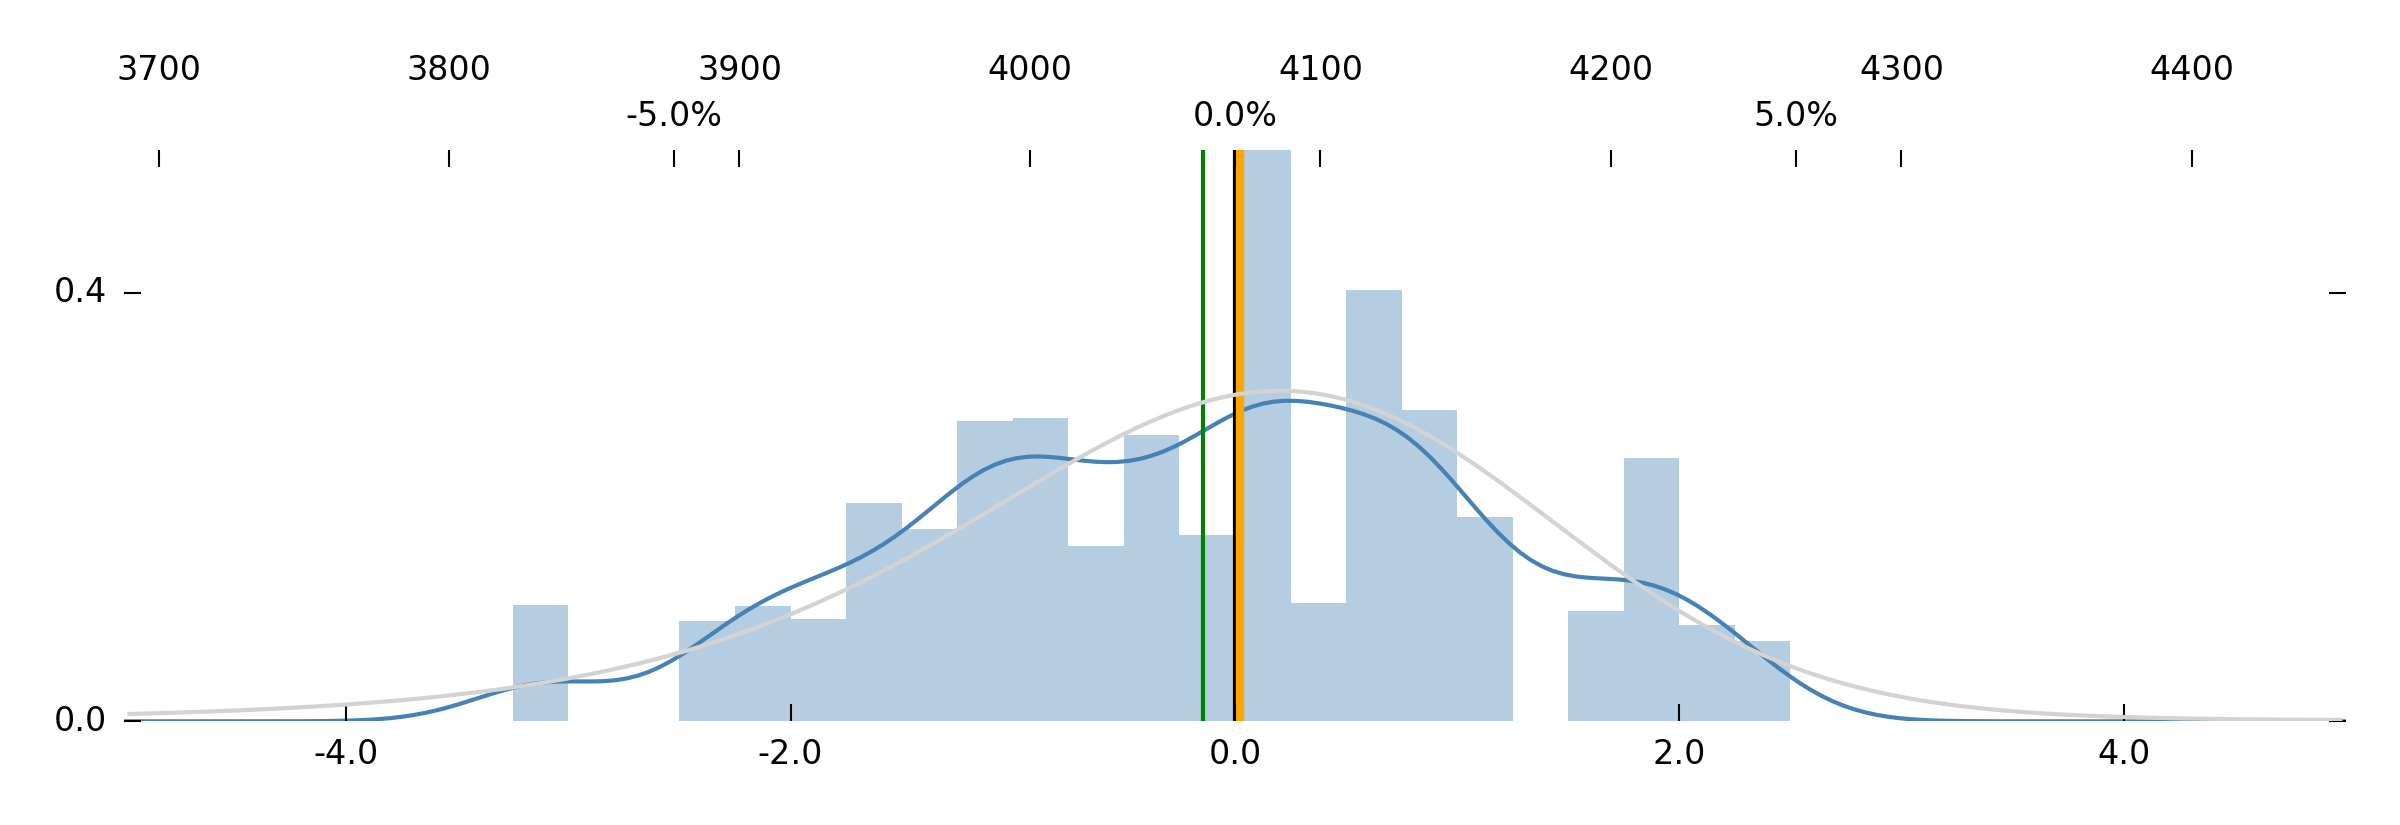
And then, lastly, if you want to be bullish, you want Robot Jim to tell you to be bullish—because he's looking at all of this data in multiple dimensions with his robot eyes and deriving a forecast from it.
And Jim just doesn't care. His forecast is the same as last weekend: "The market is mostly right and there is no edge."
Jim maintains the tiniest bearish leaning, which, for Jim (trained on a period of mostly bull markets), means he's actually a bit more bearish than "neutral."
A couple "Strategic" thoughts: Our idea that bond losses would trigger very bad equity returns still stands. Just look at TLT for our "benchmark" on this topic—it's been flat. Mix this with this week's FOMC meeting and you get potential for a selloff in bonds—possible if the Fed revises the expected "path" of inflation. This potential for a selloff is [more-or-less paradoxically] increased by virtue of the decrease on rates vol (MOVE 160 -> 100), since that market is ostensibly less-ready for scary surprises.
Overall, the feeling of stability in rates carried through to a feeling of bullish FOMO in equities (remember that we think equities are the "long vol" component, the speculative component, of the 40/60 portfolio now, so it makes sense that this would happen). But FOMO is of course a mincing bullishness; a fleeting, nihilistic, non-committal bullishness that will run scared if things don't turn out well.
And so, "Strategically," now finally feels like a pretty good time to buy a put again. VIX is 18, and we just went through a litany of "meh" to "bad" data. This seems like good risk-reward.
To boot, since vols are so low, it seems like a reasonably time to buy something a little longer-dated than one week (e.g., a February EOM 20-delta put), to let our "Strategy" play out and benefit from potential vega gains.
So let's plan on that. A bearish, long vol lean.
Now, about that data.
Pajama traders rejoice
The single most common data request that we get: "Can we get NPD earlier than 7:00am?"
Our answer, until now: "No."
But we think we've found a way—and after a couple weeks of playing around and verifying that it works, we started running all our stuff a bit earlier. As of right now, we have a fairly reliable source of SPX open interest changes by around 10:30pm, and we have what we call "archival-grade" trade reports ready to process around midnight.
Once we run through all that data, compute vols, fit realtime vol surfaces with every new trade, and mark every incremental trade against that continuously updating surface (etc., etc.)—it's nearly 1:00am.
But this means that the pajama traders, night juniors, front-runners, and Australians now have something to look forward to.
So, quants, update your scripts. All GEX+ data should now be populated by 1:00am New York. Grab it from the API and do your dirty midnight magic on it.
https://squeezemetrics.com/monitor/api/yachtclub/gexplus?key=YOURKEY
Any questions—let us know!
Enjoy the week.
The SqueezeMetrics Team