All the charts and data we refer to can be found on the Yacht Club page.
Hey everyone,
That was tiring.
But we're not done yet. Let's take a deep breath and start with a few quotes from the
first note of 2025—because now is a good time to revisit them.
- Why is all of this about Trump? Because it is. We wish it weren't—but it is.
- Objective truth is for the naive. "Fake news" is everything.
- Taken together, it looks like it'd be a good year to carry long vega.
- Will this finally be the year that the stars align and we can get long bonds? We'd like that.
Let's think of each of these as "themes," and less address each of them in turn, as they relate to what's going on right now.
It's all about Trump
We'd like to tell you that it's not about Trump, because we've spent many years arguing that positioning and flows matter more than people and news. But we can't really argue that here.
For a few weeks, we've been saying that The Donald is playing "chicken" with the market, and that he's "winning." This, along with the low-VIX decline in mid-March, made fertile ground (
3/30) for a decline. We were fortunate to be positioned for it when it happened—but then after it happened, the "game" necessarily changed (
4/6):
[W]hat you are experiencing right now—is a trust fall.
This "trust fall" is a dramatic flourish. "Don't panic," he says. You will be rewarded if you trust in Trump! Many others have already pointed out that this is a very churlish, Dale-Carnegie–esque way to "influence people"—to essentially fix a problem of your own devising. But smart people, at the same time, do generally accept that the best way to have influence over people is not to give them something, but rather to have them give something to you. Then they feel "invested."
Are you "invested" in Trump?
You can see how this is an appealing way for a man to organically make his friends richer (and his enemies poorer). If you don't like him, you don't want to trust him, or invest in him. If you do like him, you may, actually get richer.
You will have already noticed that we saw this "trust fall" play out this week: Before reversing most of the tariffs on Wednesday (sparking a historic +10% day), Trump posted (on TRUTH Social) that it'd be an awfully good time to own stocks. Indeed it was.
Are you "invested" in Trump now? Do you trust?
Objective truth is for the naive. "Fake news" is everything.
"Trust" is subjective. It's a flexible concept. Children "trust" their parents. Customers "trust" their financial advisors. The victims of Stockholm syndrome also "trust" their captors.
It's important for us, navigating this market, to identify these trust games for what they are. It's a drama. It's fake. It has nothing to do with objective truth. And where this becomes important is that if you actually start trusting Trump, you're eventually going to get burned.
We've already put forth one possible ironic outcome for how Trump gets steamrolled by his own hubris (he gets rid of inflation [yay!], gets the rate cuts he wants [winning!], and then we deflate into oblivion because lower rates are actually deflationary right now). Be on the lookout for things like
this.
This would be ironic. This would blindside people. This would be the most ironic outcome for Trump trying to bend the market to his will.
Right now, being "long Trump" is like being "short vol." It'll probably work—but if it doesn't, it will be in a big, scary way.
And in light of this, we can repeat...
[I]t looks like it'd be a good year to carry long vega
And it has been already!
But this isn't an absolute, of course. Like we were saying last weekend, "the time for convexity is already over" when VIX is 40. But if the market starts getting buoyed up on news that Trump is patching the hole he kicked in the wall and VIX falls below 30, you've really got to consider the case for long volatility again.
Indeed, we think that the best "opportunity" in this market would be if the S&P is able to rally, and VIX is beaten down. So far, VIX has been aggressively sold on S&P rallies (see Wednesday), which seems kind of stupid—but it'll probably happen again. It would gladden our hearts to buy back into some ATM SPX puts or VIX futures if the opportunity presents itself.
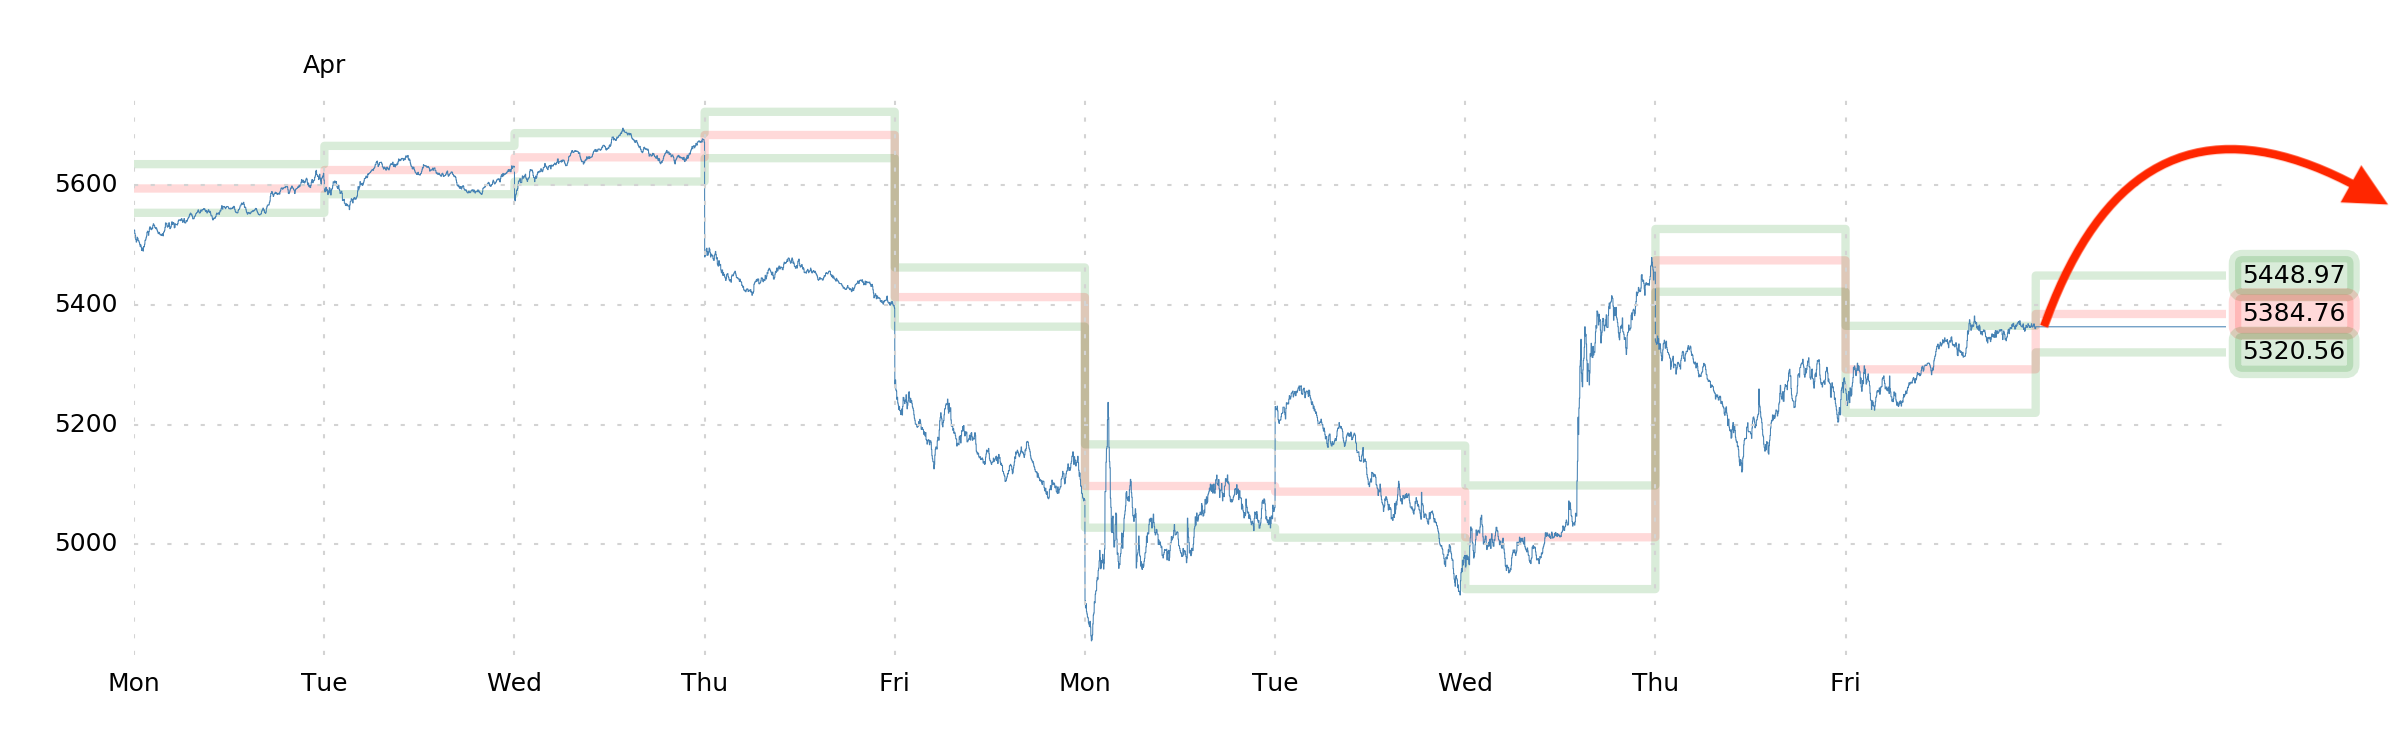
As long as we're talking about this—and at the risk of sounding too hand-wavey—we envision something stupid like this for the coming week. (And there already appears to be a pump underway.)
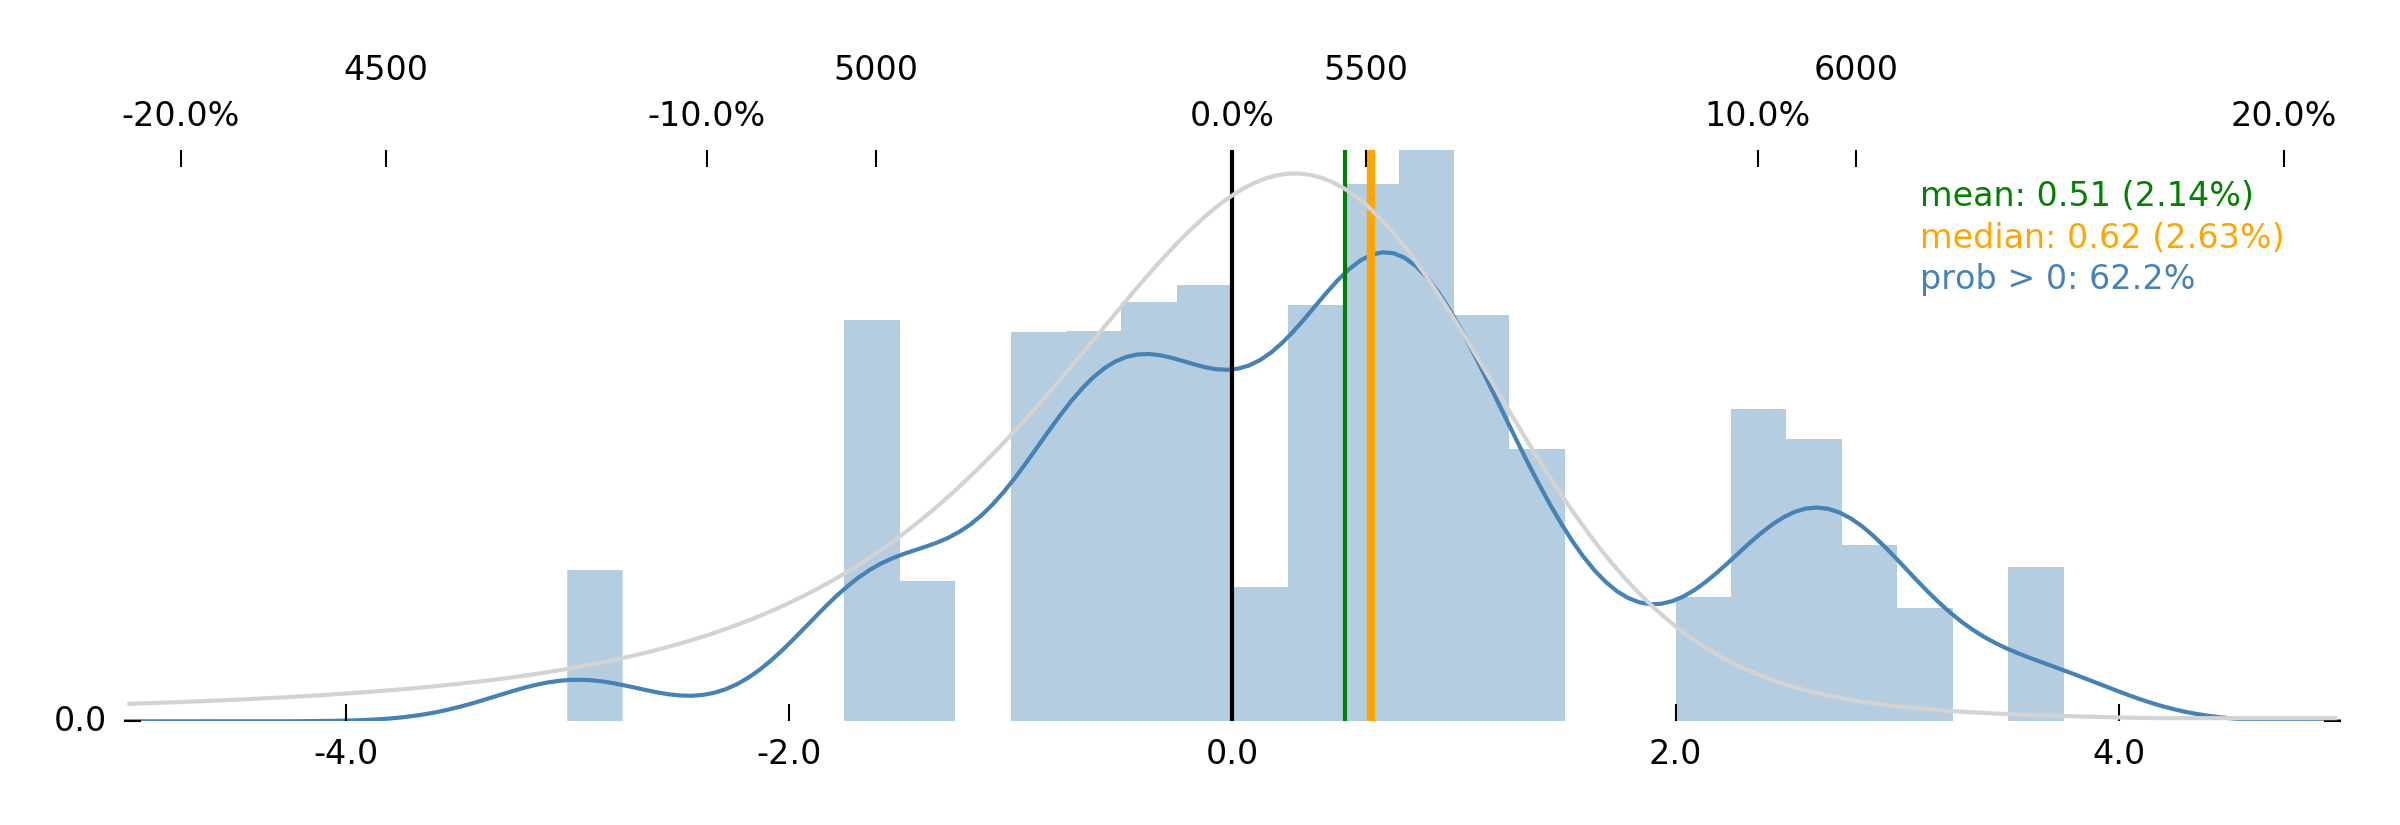
Somewhat supportive of this sentiment is that Robot Jim, as on Friday morning, is feeling a bit more sanguine and is leaning visibly bullish. A median 1-week return of 2.63% is quite respectable, actually, and that huge lump of probability up at +10% is mouth-watering.
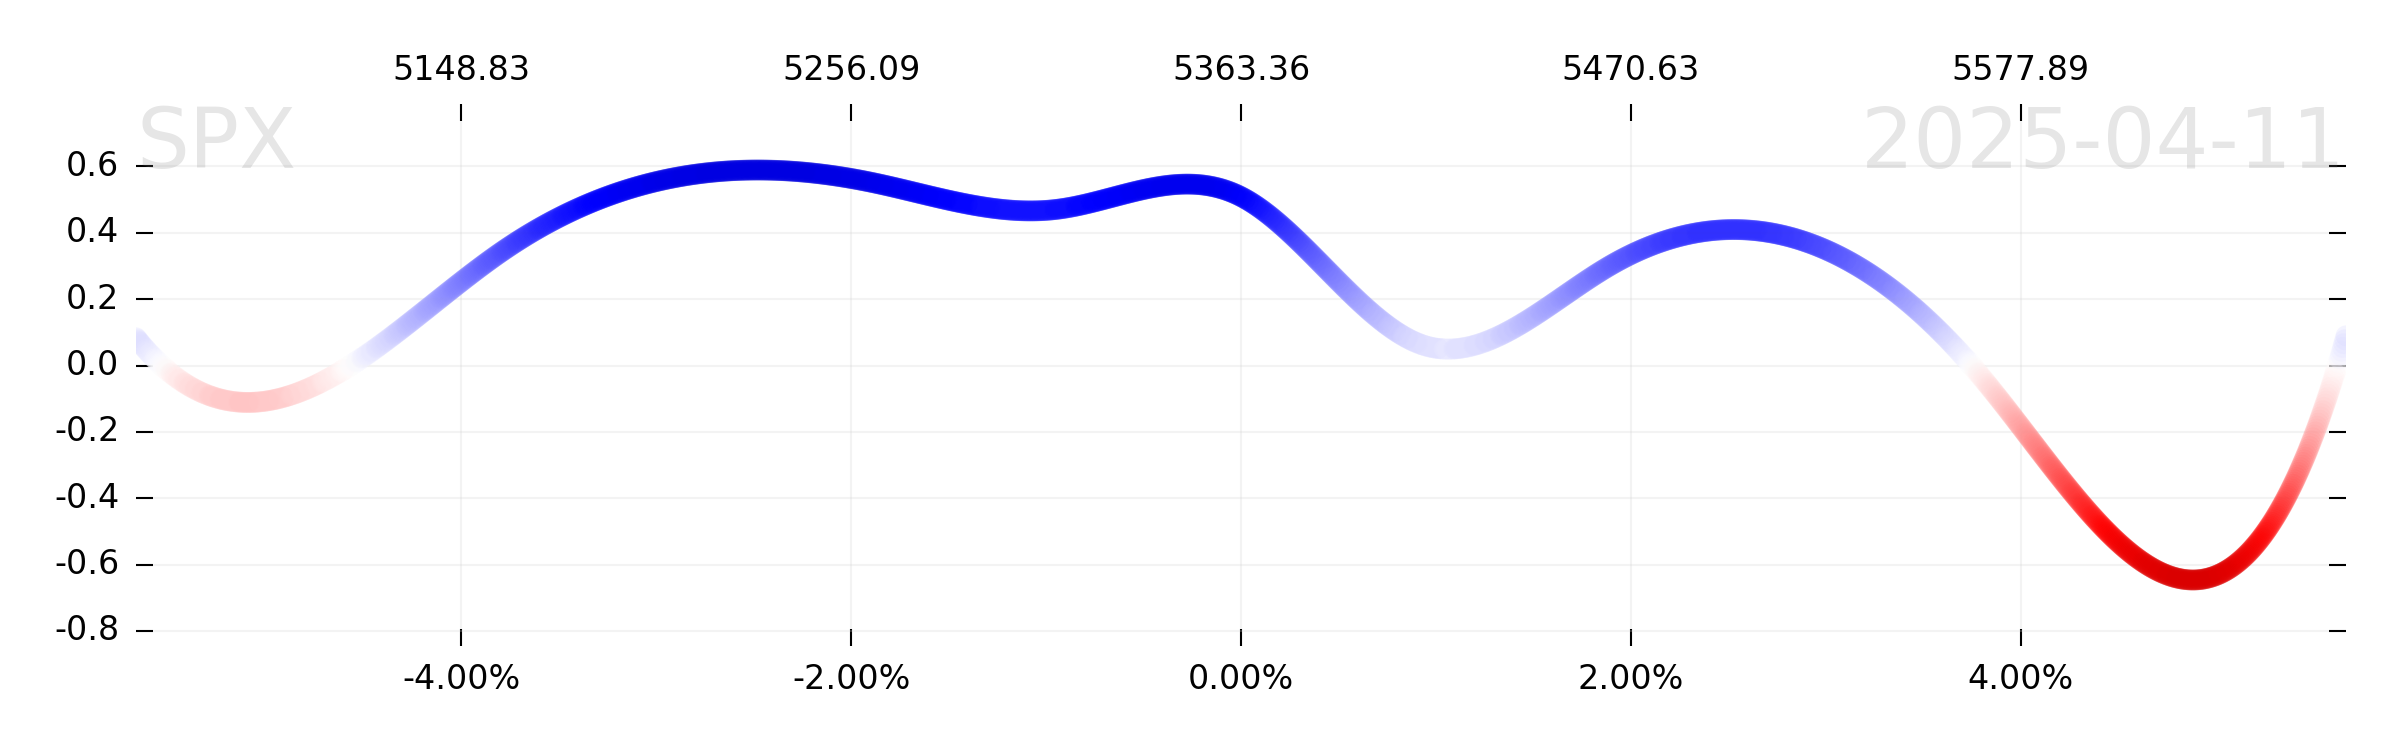
However, there seem to be some limitations under the surface of this forecast. A sufficiently rapid move to the upside (i.e., a >4.00% gain on Monday) would trigger Jim to quickly reverse his outlook.
This isn't surprising, since high realized volatility tends to keep a lot of traders deleveraged, so a rapid move to the upside keeps a lot of the usual suspects ("vol-control," "momentum," "risk parity") away, and prevents momentum from being re-established.
Again, we would love to be able to get long vol again, which we've already had considerable success with, and it looks like we may have that opportunity this week.
Now for the thing we haven't had considerable success with...
[L]ong bonds? We'd like that.
We were so patient! We waited and waited. And then a little over a month
ago, we finally got long bonds. We got long UB and ZB futures with TLT above $90.
TLT is now, after this past week, $86.89.
So that hasn't gone well. And yet, we see no reason to shift our outlook. CFTC
CoT report has more dealer short contracts than ever (190k Ultras!).
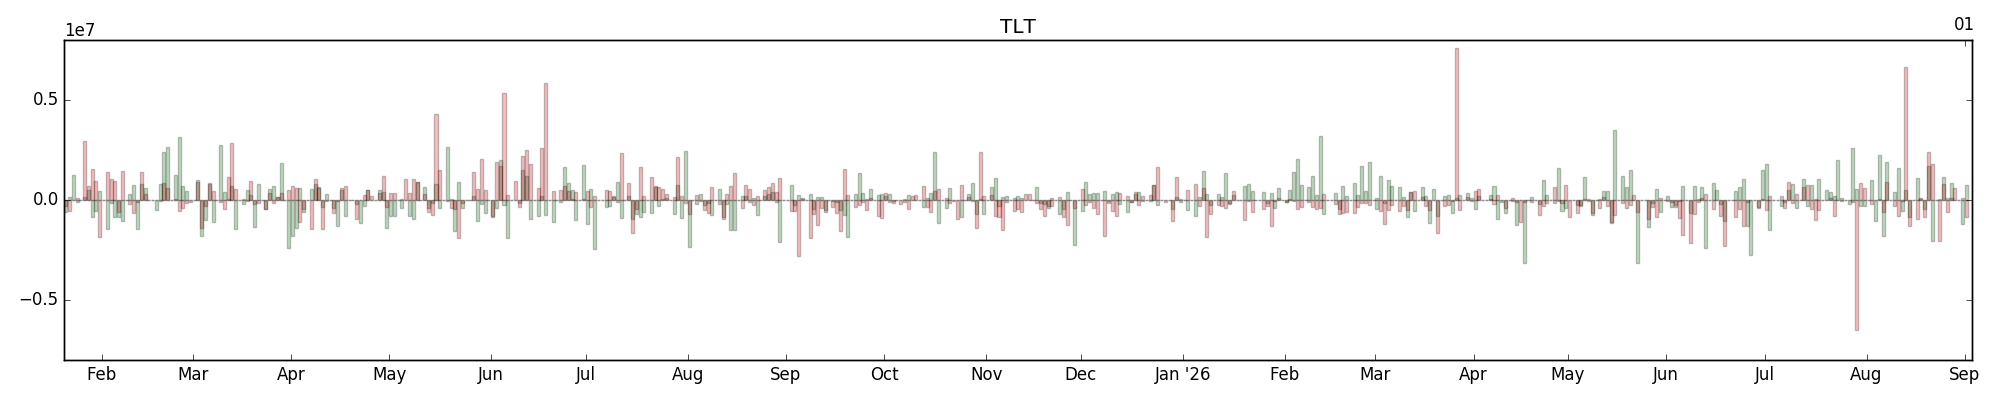
Oil and commodities are down big in the past month. TLT
option flows have been net negative delta in the last week.
All of these are independently good signs to be long those bonds.
Why did the bonds go down this past week? It depends who you ask, of course, but the one compelling explanation being bandied about is that the "pod bros" are to blame ("swap spreads getting liquidated"—regarding which we've now seen a couple Bloomberg headlines). That's sensible, but we also wonder if there were some (non-TLT) derivatives bets (especially short puts) that got hurt as bond volatility (MOVE 140) spiked (thereby lowering the deltas of sold puts and compelling dealers to sell bond futures), and then that all came home to roost this past week.
Does that make us want to change our tune? No—not at all. Rather, it makes us believe that the trade is all the more likely to work ("weak hands" have been carried out). Tariffs aren't likely to be genuinely inflationary. Recession is perhaps a coin-flip probability at this point (which is high!). Deflation, borne out of recession and boosted by weird monpol effects and AI, is a real and underappreciated possibility. Everything points toward "be long those bonds." So we're long UB and ZB futures. We even bought more this past week (yeah, we know, losers average losers). Wish us luck on that.
So, in summary:
We want SPX up and VIX down, and then we want to buy some volatility. Maybe that means long VIX, and maybe that just means long SPX puts. We will, necessarily, play it by ear. And at the same time, we want to be long and strong 20-year+ Treasuries. That's it.
A final philosophical word:
We aren't being facetious when we say that all of this is a "game," and "subjective," and "fake," and we really do think that you need to equip yourself with a harsh cynicism if you want to understand what's going on and to succeed at your job right now. This comes at a cost, however, in that you may start to identify yourself with the sharp-edged intellectual tools that you must use to navigate a harsh market.
Indeed, cynicism is a tool, not a personality. Irony is a sad truth—it's worthy of a sigh, but not worthy of bitterness or schadenfreude. Don't become the tools of analysis that you must use. Equip the tools, and then discard them. The workman does not eat his dinner with a shovel.
So whenever you're given the opportunity this week, go hard in the opposite direction. Listen to Beethoven's 6th. Take a walk in a pine forest. Seek out some moss and stone and dappled shade. Pick some wood sorrel. It tastes citrusy, you know. Isn't it all so grand and beautiful?
Then, dear reader, get back to slamming the offer on some bonds!
Enjoy the [short] week.
The SqueezeMetrics Team