All the charts and data we refer to can be found on the Yacht Club page.
Hey everyone,
After a string of pretty great weeks, this past week was a loser—on multiple fronts.
First of all, the forecast didn't play out; and because the forecast didn't play out, we lost some money. And second, we got so bogged down in a bunch of weird mathy details that our work on VXX/TLT went absolutely nowhere. So unless you like Nietszche, don't read the third section.
- T minus 5
- T plus 5
- T is a flat circle
T minus 5
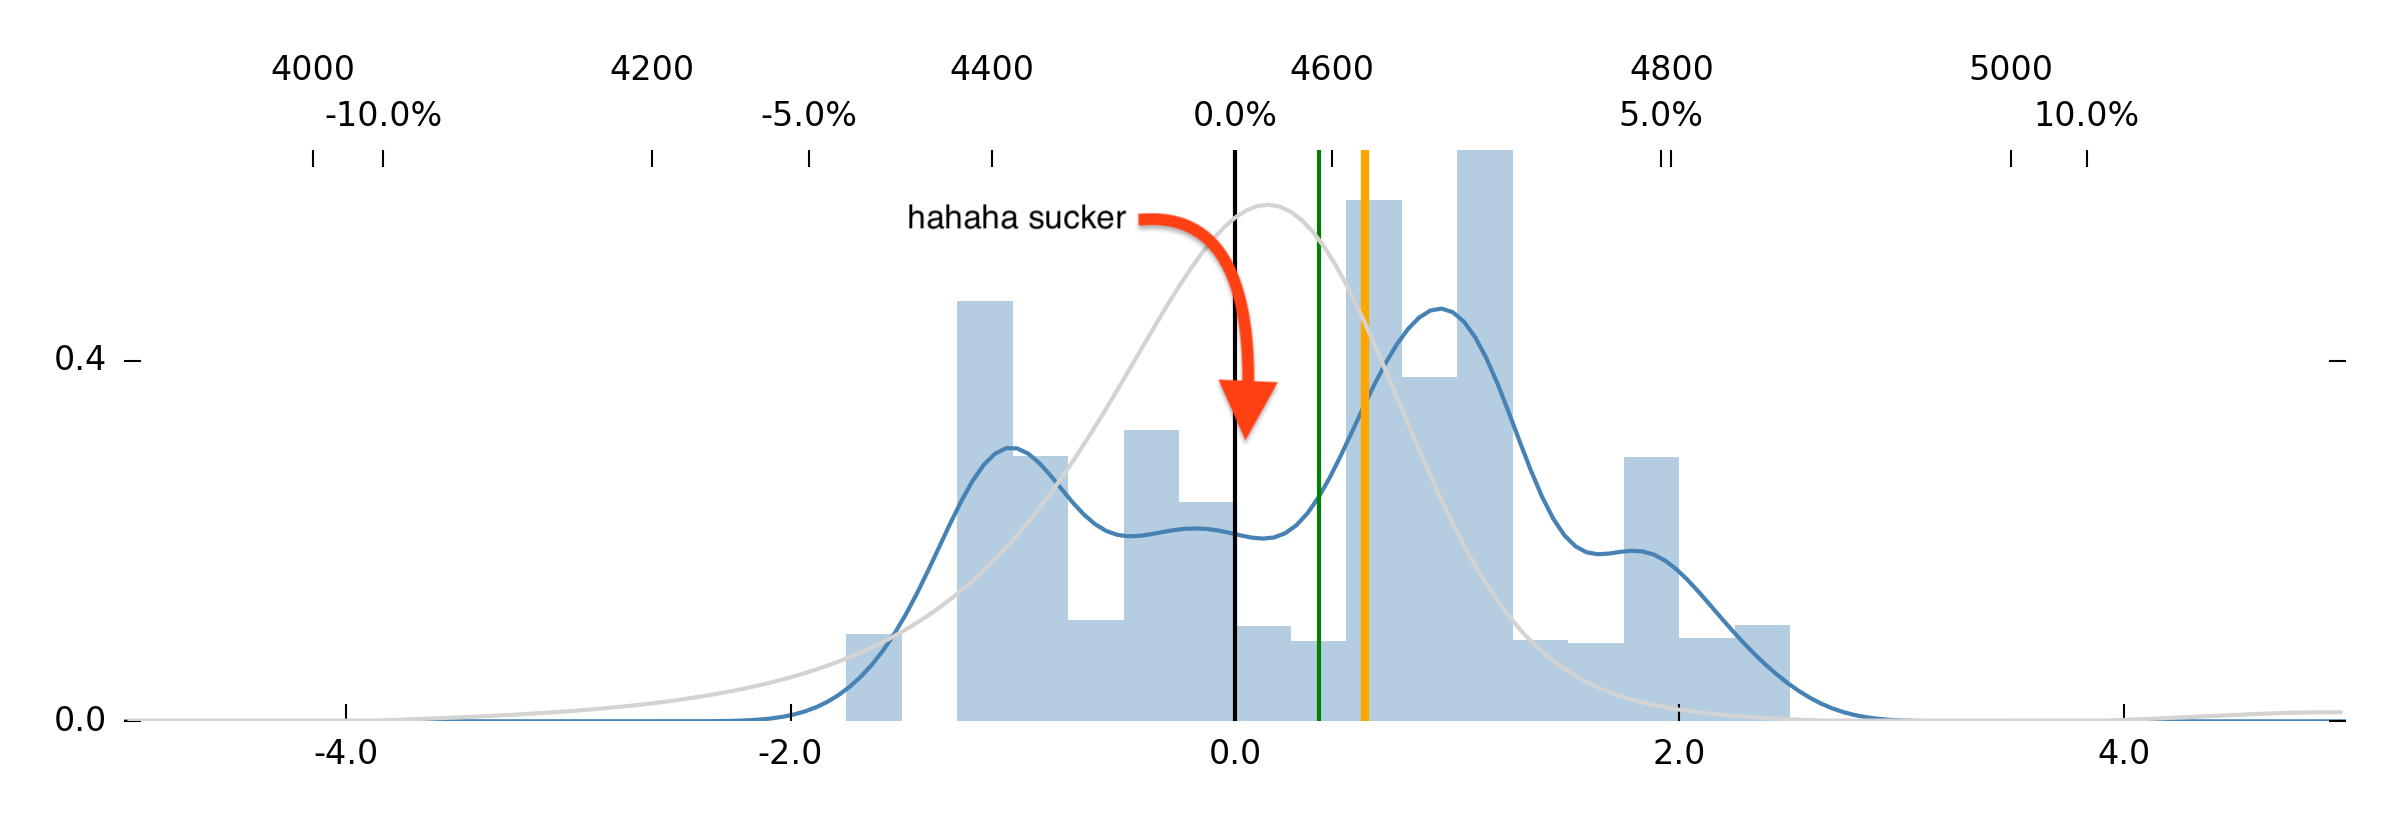
This is what our forecast looked like, and where we landed on it:
That's because the week returned a mere +0.06%, landing at SPX 4546.
Here's what we said about that possibility last Sunday:
Two outcomes are underpriced: Landing at ~4650 in a week, and landing at ~4400 in a week. One outcome is overpriced: Staying at 4500–4600.
Well, we definitely stayed at 4500–4600. So that's not great. We could not have been more wrong.
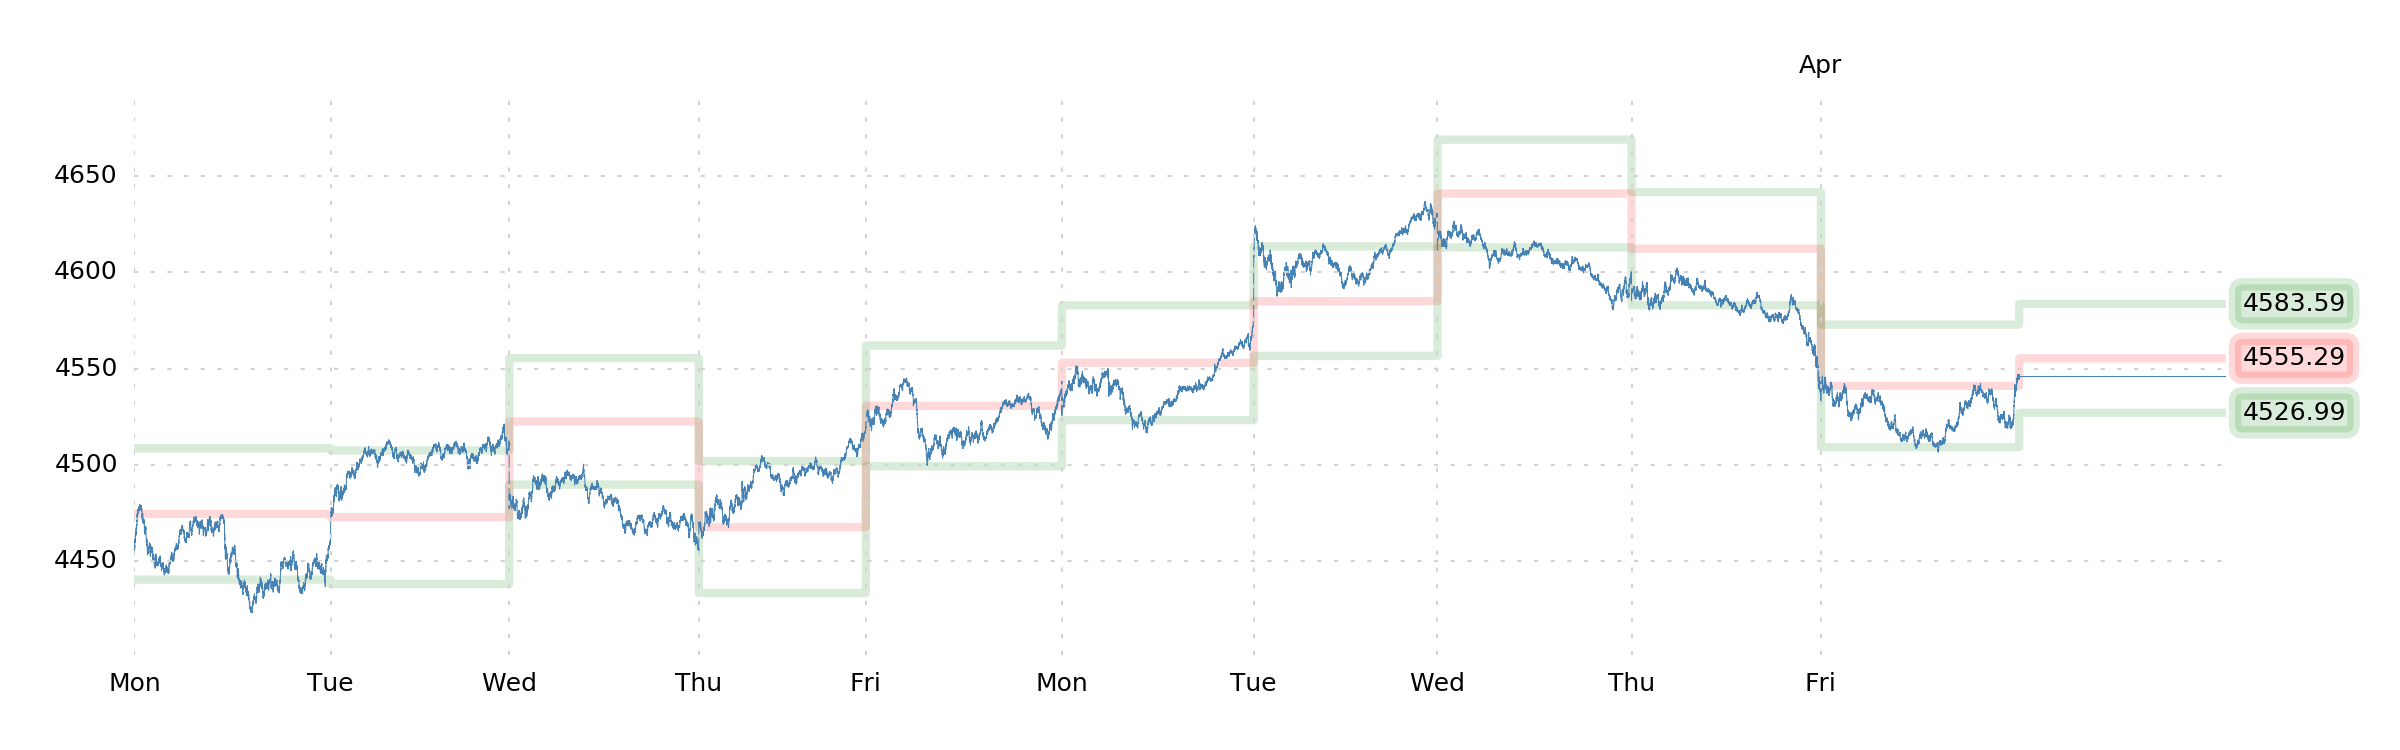
While we're at it, let's bask in the particularly delicious circumstances of our 4600-struck calls, expiring on Wednesday. Where did SPX settle on Wednesday? Yes, 4602.45. Our calls settled a little over two points in the money! Wow! Paydirt.
Now, what fresh disappointments are we going to subject ourselves to in the next five days?
T plus 5
All we've got right now is a smattering of call spreads, which are betting on SPX rising above 4600 by this coming Wednesday or Friday.
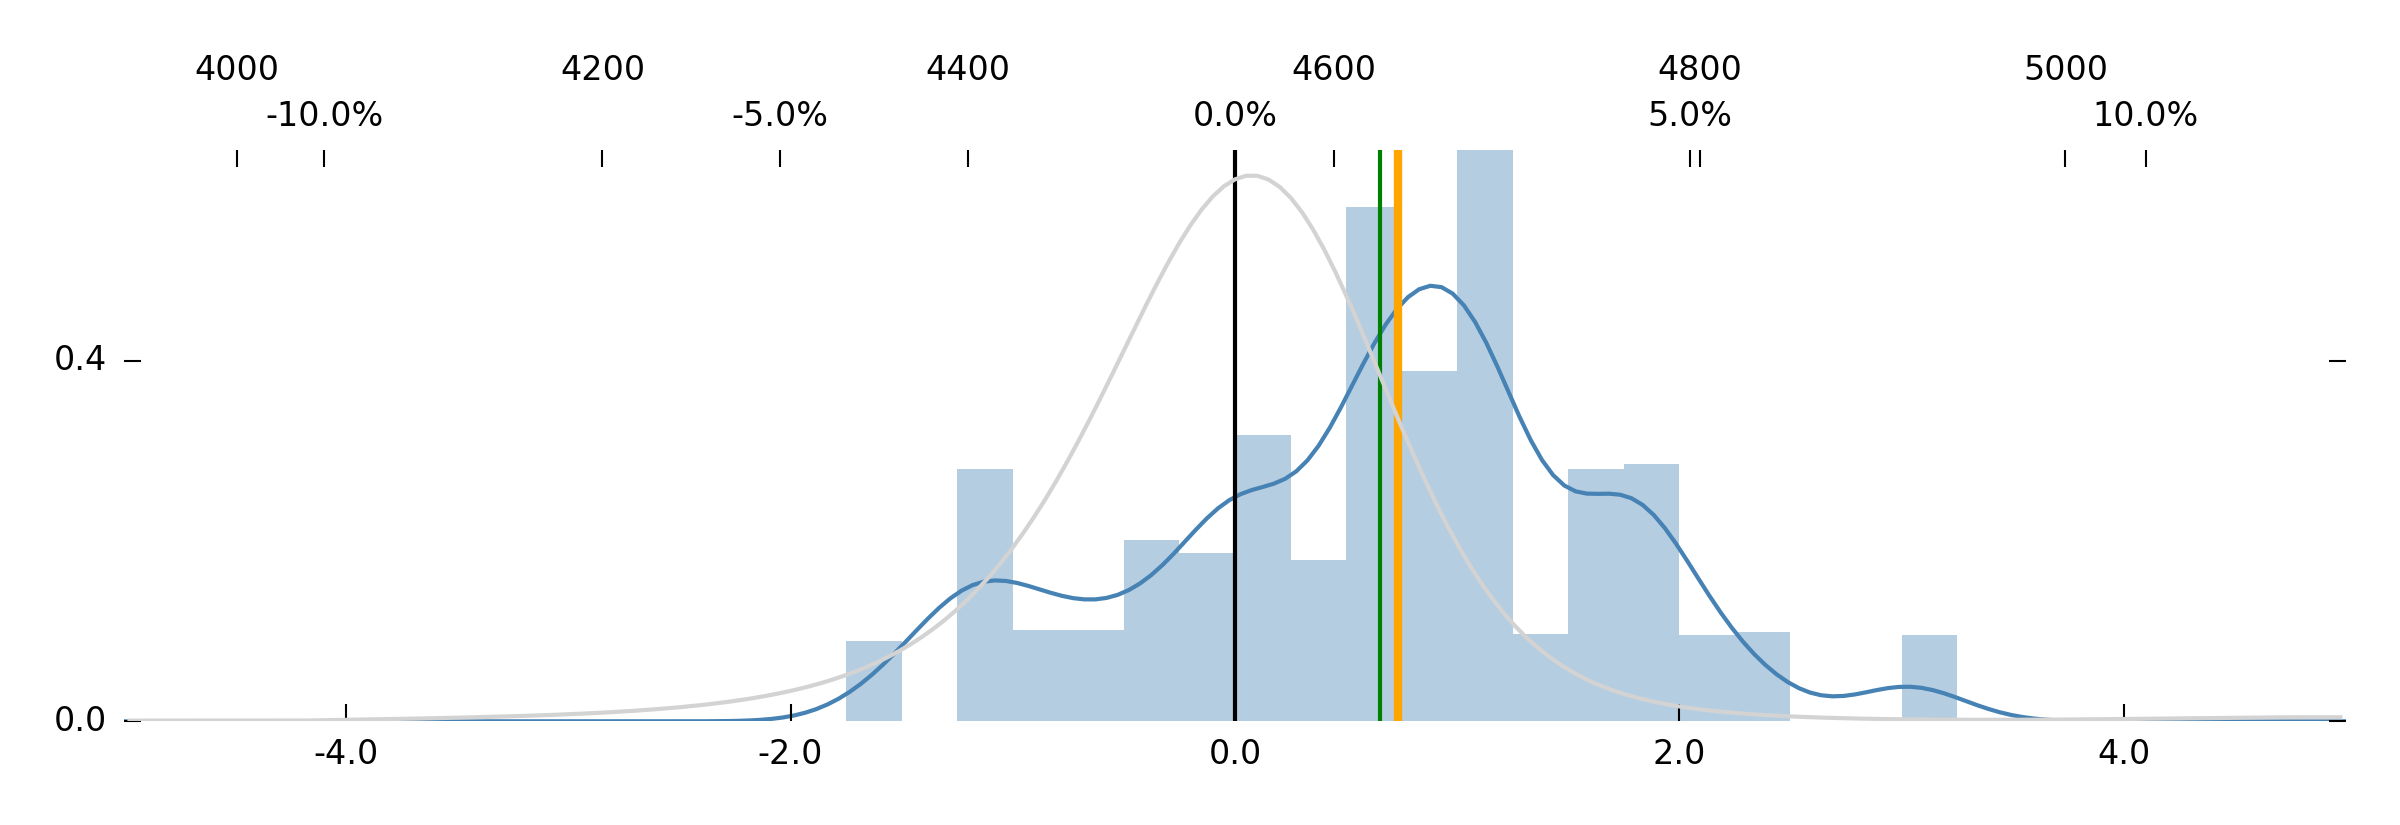
Fortunately, this jibes nicely with what Robot Jim is predicting, and where our edge appears to be:
This is a decidedly bullish distribution. The mean and median are forecasting a weekly average gain of around 2.00%, and the bulk of our perceived mispricing is in SPX landing above 4600, and even the possibility of making a strong move toward ~4750.
And with SPX vols still rather low (VIX remains under 20), we're encouraged, implicitly, to be bullish and long gamma at the same time. I.e., long some calls. Put simply, the probability of SPX shooting up to, e.g., 4750, is under-appreciated by market prices.
But a more conservative approach, striking a long call ATM and a short call ~4700, still manages to capture a lot of edge, and it may be more suitable to your desired win-rate. Like we said last weekend (which was ironic, given how our OTM calls performed):
Though it's also worth mentioning, again, that the best bet from a true expected value standpoint is still to be long some OTM calls. It's just that this has an inherently lower probability of profit (i.e., high probability of disappointment), so it's nice to diversify away from this a bit. To spare our fragile egos, mostly.
Anyhoo...
- DIX is still bullish. People are still buying stocks in a big way, as they've been since late January. You can rationalize this however you like. Our explanation is that "There Is No Alternative" has never been stronger. Do you want to be in cash as inflation rages? In a money-market fund as the Fed Funds rate gets ramped? In global equities as War (and Pestilence, and Famine, etc.) comes from the East? In 30-year Treasuries as they whisper about yield curve steepening policy? It's all bad.
- NPD is still scary. Despite buying stocks, folks aren't buying protection for those stocks. SPX Net Put Delta has been cruising around zero now for several days. At this point, it's enough for us to say it's actually concerning, because it means that customers have actually begun swapping positions with one another, and bypassing market-makers. And when market-makers get bypassed, options get mispriced (and when options get mispriced, nasty liquidity disconnects / vol-of-vol occur).
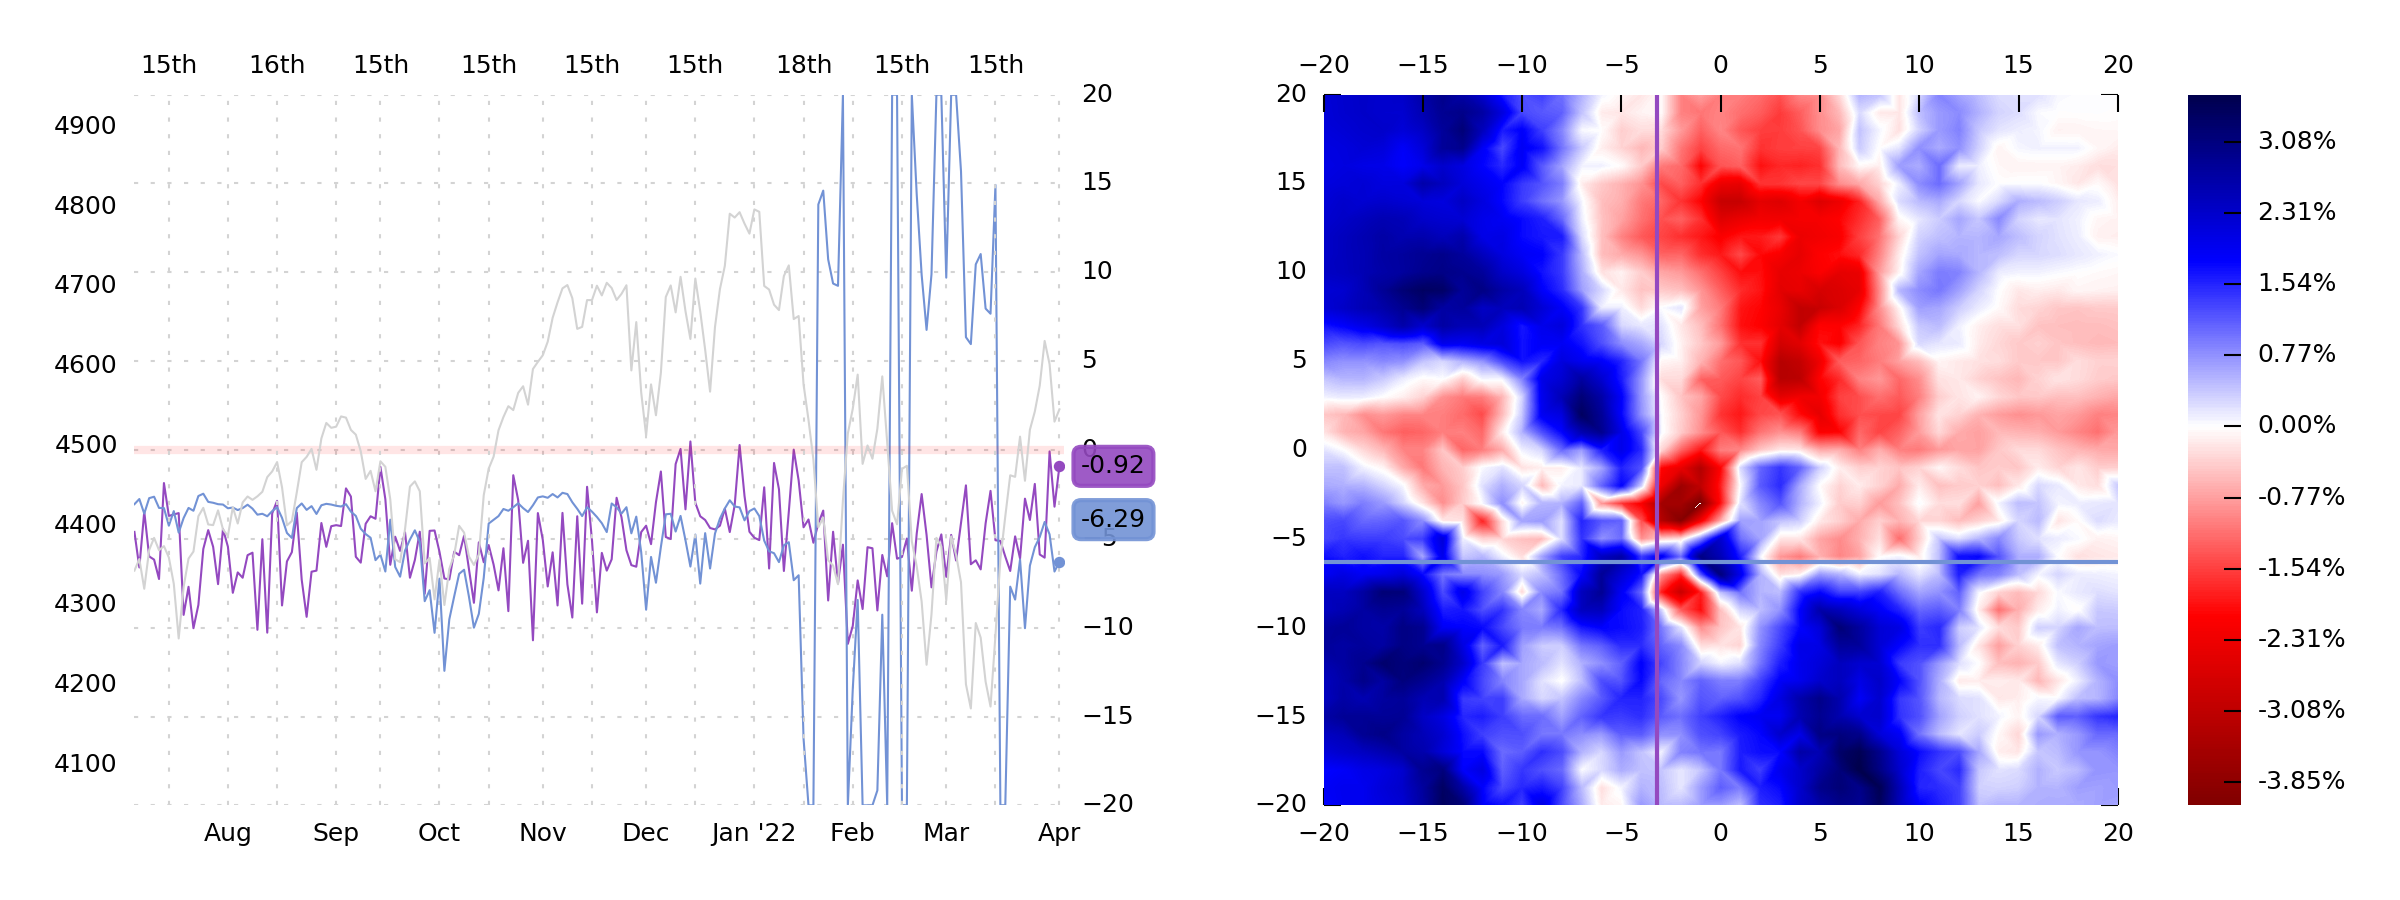
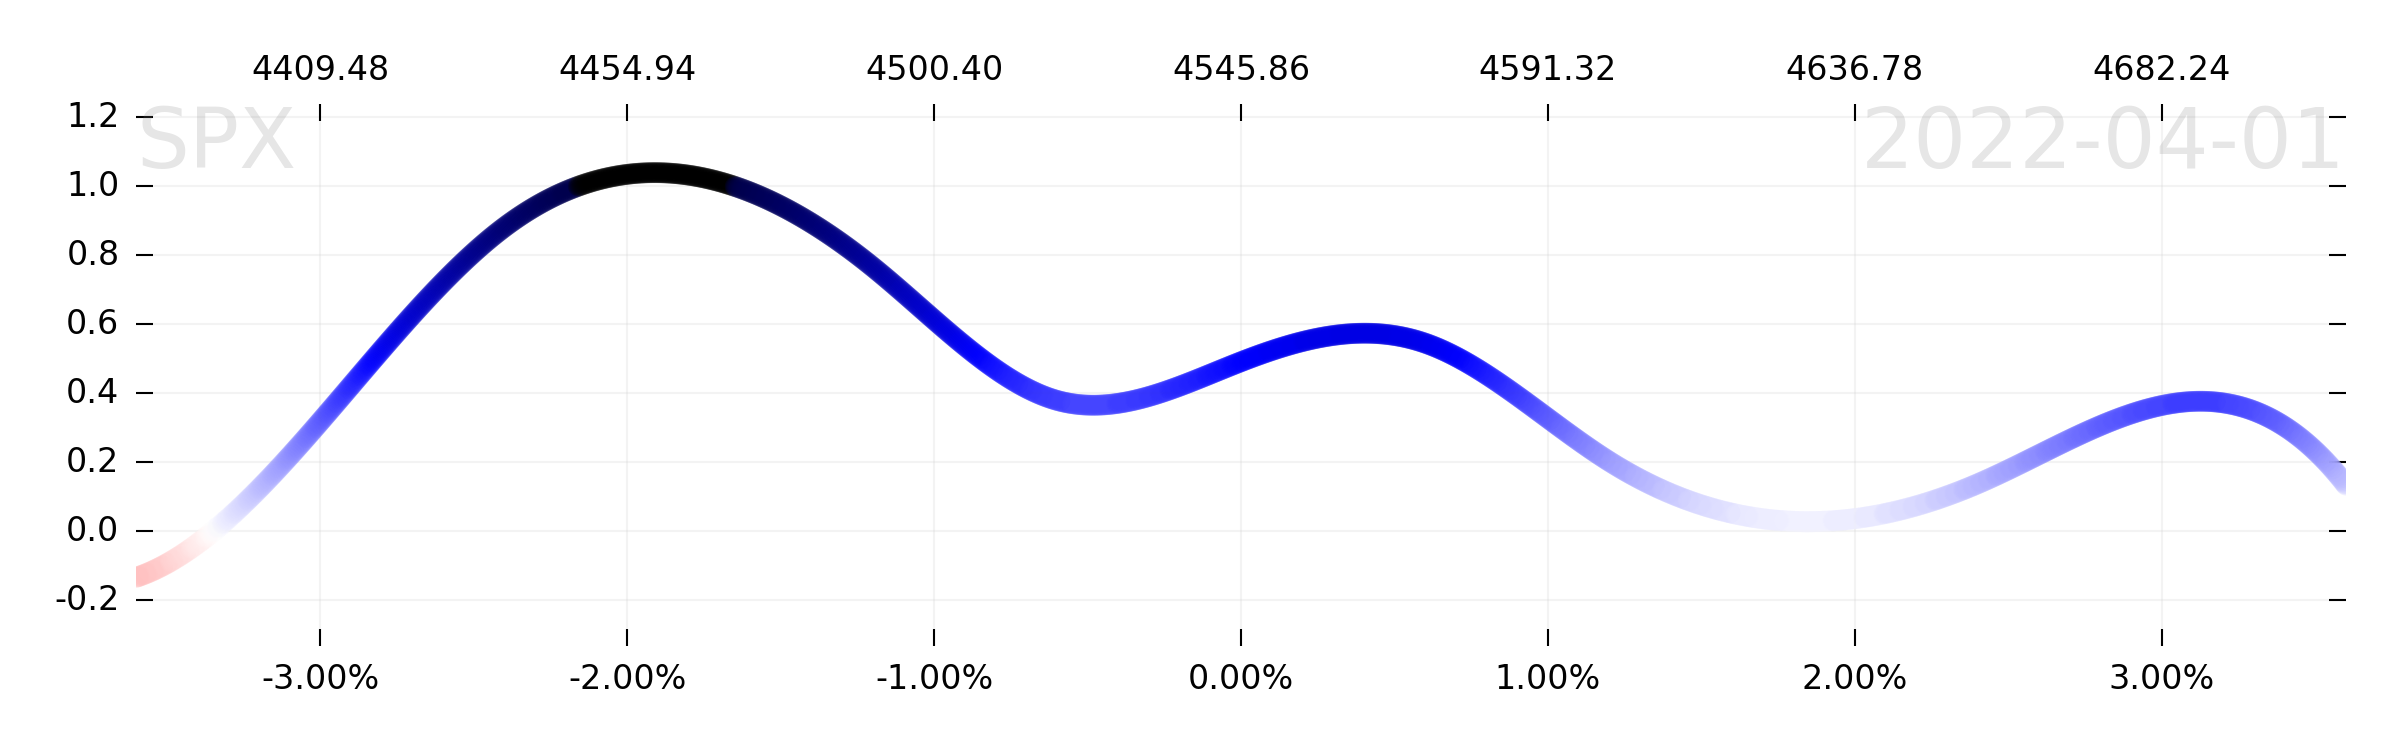
Taken together, this means we want to in a bullish, but fixed-risk structure. I.e., calls and call spreads. And that's we're at already. Nor will we be easily deterred, or likely to change our minds quickly. Note that the step-forward curve below doesn't lose its bullish leanings unless we get a +2.00% day tomorrow. And a -2.00% would just make things more bullish.
So as uncomfortable as it is to say, we're actually planning on sizing up our positions in the morning. We've been pretty conservative this past week—but the edge that Robot Jim is showing us right now is pretty big. It deserves a bigger gamble.
So wish us luck. Hopefully, at this time next weekend, we'll be writing something very smug and self-assured.
T is a flat circle
You're treated to another stream-of-consciousness this weekend.
First, something self-congratulatory: Somewhere up there at the beginning, we said that "because the forecast didn't play out, we lost money." This is really cool to be able to say, and it's really important. It's also the reason that options (and their precision) are really cool.
Last weekend, we expressed a rather specific belief that the market was undepricing the possibility of SPX rising above ~4600 and staying up there. This specific belief was borne out of a rather complex and painstakingly constructed system with multiple data inputs.
In seeking to optimize that perceived edge, we took a specific risk, and lost nearly everything that was gambled. This is normal for us, and in a good trading system, we would argue that it should be normal. If we continue to execute on what the believe actually has edge—even if our probability of profit is low on individual bets—we expect to come out ahead. Way ahead, hopefully.
Hence, we commented above somewhat wryly on the "ego" being the only good reason to take higher-probability bets. We ought to be comfortable with a low win-rate. Other people aren't. We should expect that there's an edge in taking advantage of everyone else's psychological crutch. They want more wins, more often. We shouldn't care.
This is all to say: Honesty is important. Not honesty with other people (who cares about other people?), but honesty with oneself. When a trade fails miserably, you should always be saying, "I'd do it again." This is the
"Dionysian attitude" toward trading. You should be perfectly happy to re-live even the nastiest of drawdowns.
Time is a flat circle. Your trading, if it's any good, exists outside of time. The "right" trade isn't always the trade that wins. Your job is to take the right trade regardless.
Yes—the above is pure mumbo-jumbo, but it's also true.
Now, where this becomes perhaps even more interesting is that the same stuff seems to be apply toward not just the execution on a trading edge, but the discovery of a trading edge to begin with.
You may recall, dear reader, that the majority of these sections of the Sunday notes in 2021 were spent flailing miserably. We failed to find what we were looking for for a whole year, but we kept hammering away at the same theme ("vol triangles"). Eventually, it all came together and Robot Jim was born. And that was worth the trouble.
So this is sort of a placeholder. We accomplished nothing tangible in terms of our research this week. Nothing at all.
We also lost on our trades.
These are necessary things. Good things, even. And we'd do it again.
*pats self on back*
Enjoy the week!
The SqueezeMetrics Team