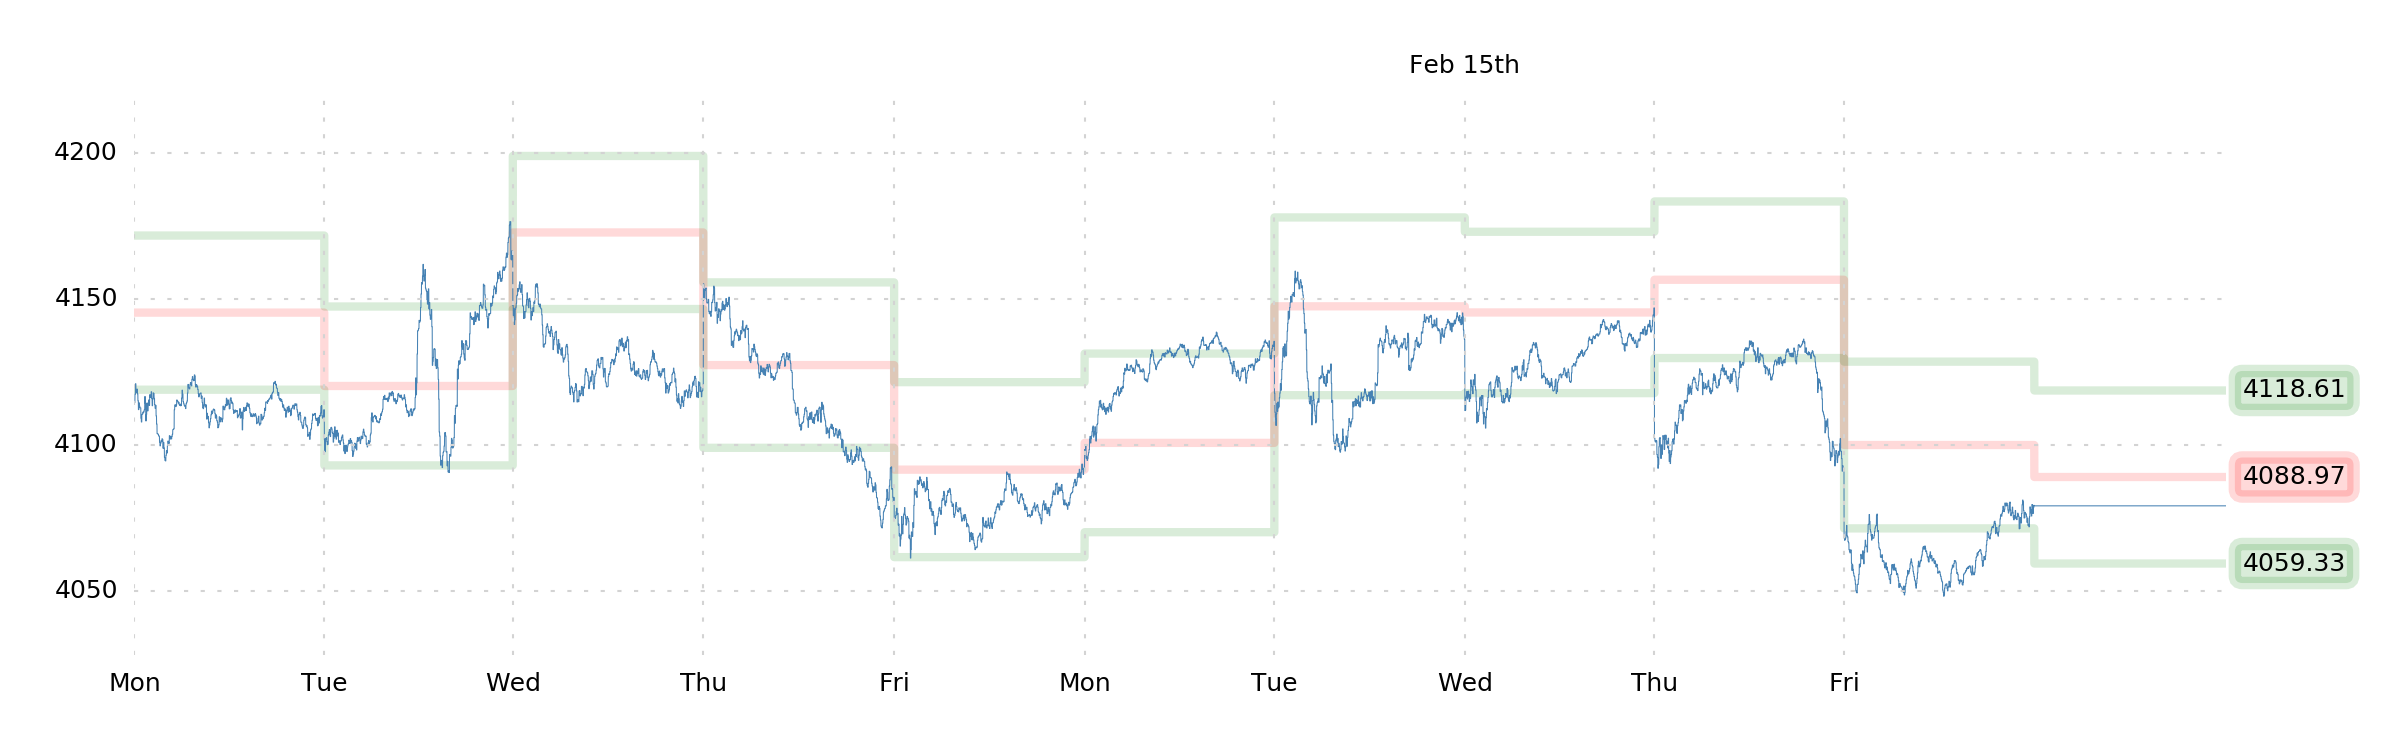
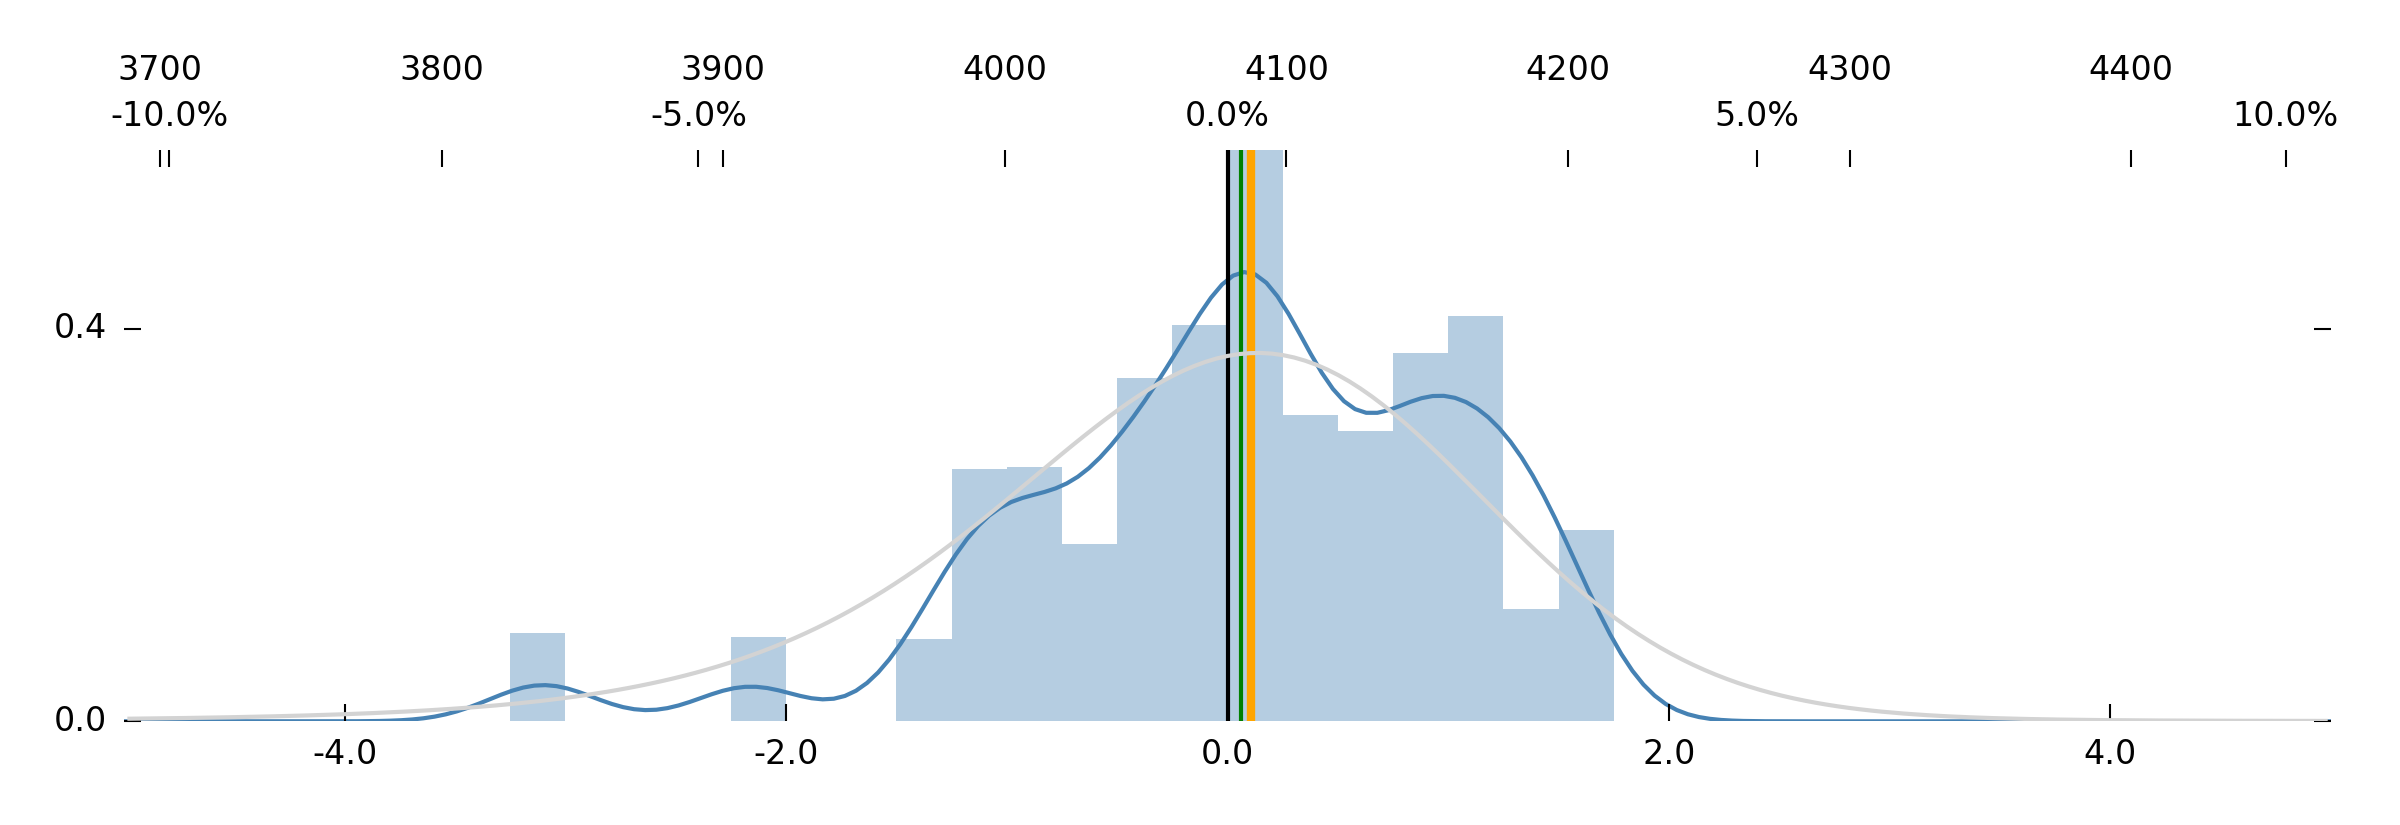
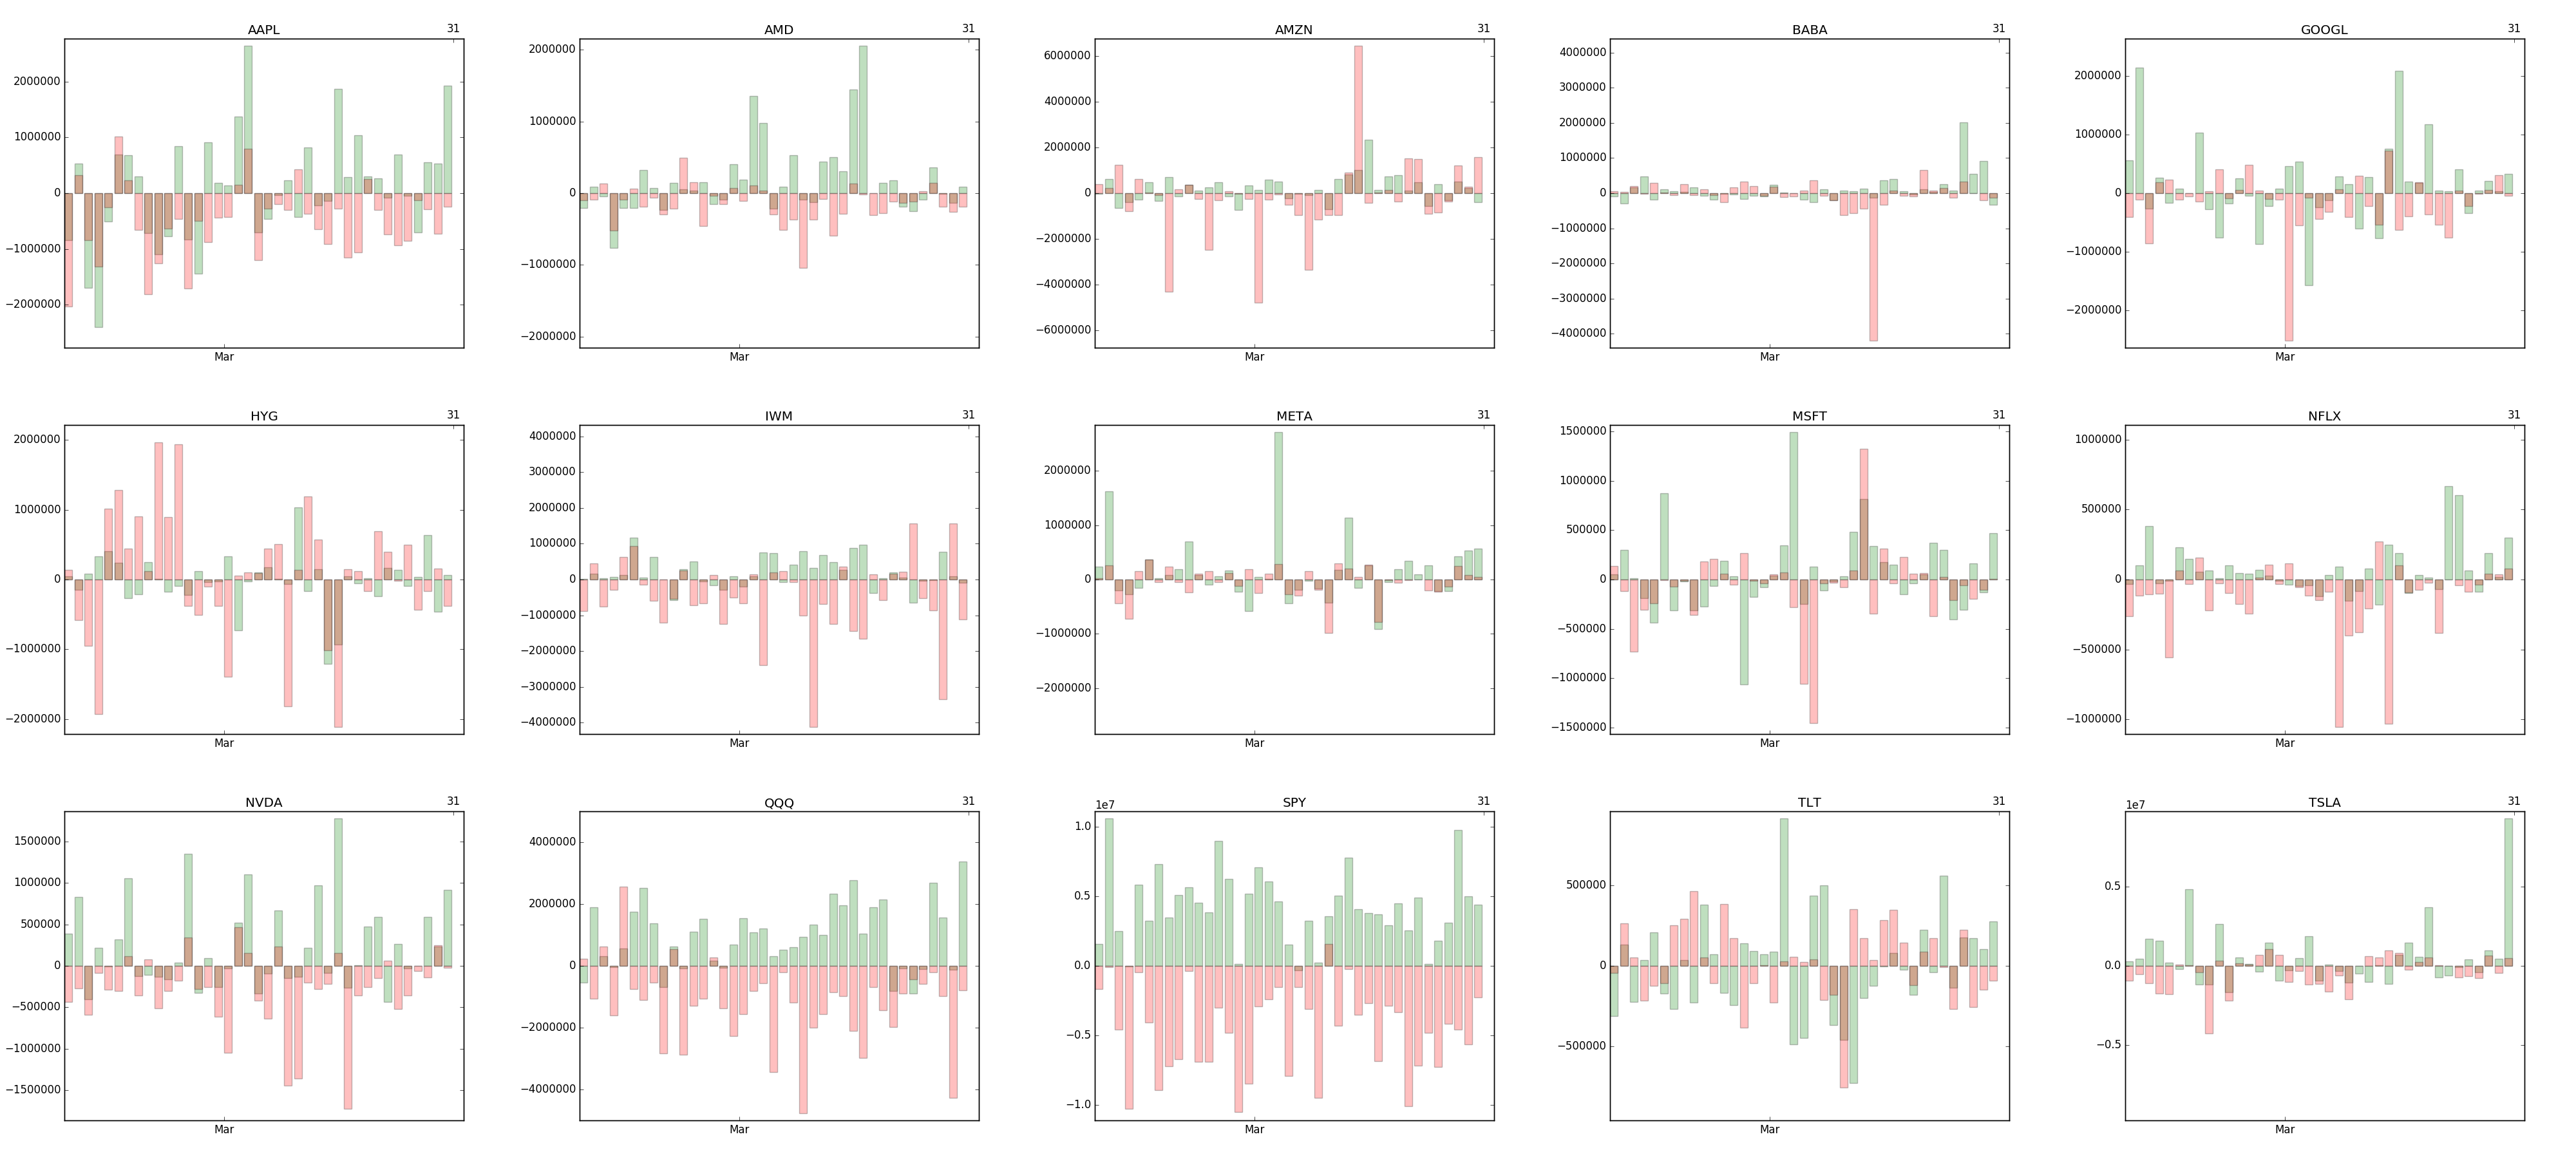
All the charts and data we refer to can be found on the Yacht Club page.
Hey everyone,
Lots of little things to cover.
The Degenerate long-option-only account is up 0.57% year-to-date. Thrilling.
With that said, we'd like to pat ourselves on the back a bit: Of the two tickers that we highlighted when we were thinking of examples for stuff to buy calls on (
NVAX and
MCFT) in the past month, the former will has ended up worth $0 on the February expiration, but the latter should have ended up worth quite a lot (stock is up 16.4%).
This is, actually, a prime example of what we mean when we say that—as long as you have some edge—the long option approach is superior. An MCFT 30-strike February OTM call could have easily been purchased for $1.15 at the time (with the most recent trade being $0.85), and would have settled at an intrinsic value of $3.99—around a 3.5x return.
We are keeping the faith.
In similar news, we forwarded a flows-based concept of near-term returns for the top 15 optionable NMS stocks and ETFs
last weekend, and we hypothesized that recent put and call transactions might favor some names more than others.
Long AAPL / short AMZN? Long TSLA or NFLX? Short BABA?
We were actually correct on all accounts, which (given that we believe our explanation to make sense) means we
might be on to something. And so, feel free to take a look at the same data from this past week (
here). The explanation is simple: More short delta transacted recently (sold calls, bought puts) means more default bullishness going forward, and
vice versa.
Overall, the data right now seems bad for bonds and stuff. And inconclusive for other things. And good for AAPL, again.
Alright, that's all we have to say about the Degen Science stuff, because at this juncture, we want to spend a bit of time reiterating our 2023 Strategy.
But first...
- The Vanna Non-Starter
- In Memoriam, Jimmy Carter
- Stupid to be Smarter
The Vanna Non-Starter
We only had one big thing to say last weekend: That despite what everyone else seemed to be saying, or implying, there was no real risk-premium in the price of volatility—and as such, we did not expect a "vanna rally" to boost the S&P after the CPI print, even if it were nominally favorable.
The proof of the pudding is in the eating: VIX fell 1.5 points straightaway, and SPX was flat to down. There was no vanna rally—no relief rally.
You already know, dear reader, that folks haven't been buying SPX puts lately. We've been making a point of this for
over a year now. It's the chief reason that we've been bearish on the S&P. It's the chief reason that you do not see bull-market price-action. Along with the rise in yields and inversion of the yield spread (and
inextricably linked to this), it's the most important thing going on.
So let's quite firmly assert, for the umpteenth time, that people aren't net buying puts, and let's understand that this affects everything that we see and expect to see in the market. Make sense?
In other news, it was another lovely week for 0DTE and SuMo trading.
And while we like to think that our bearish bias for February is proving correct—we still haven't been suitably paid by our end-of-month put position (now re-upped twice).
Shout-out to Robot Jim, who continually (and for what seems like forever) recommends not getting involved in directional biases. Market's flat for three weeks now, so cheers to that old silicon nag and his annoyingly useful forecasts.
In Memoriam, Jimmy Carter
The Monday holiday is owed to George Washington, but according to the news, former president Jimmy Carter will also soon be burning your theta like George Bush Sr. did in 2018. Weirdly, everyone is acting like he's already dead, but vol traders know the truth: A former president has only officially died when an ad hoc market holiday is slapped onto the calendar.
So, keep that in mind. Update your vol models.
Tuesday's 0DTE dealer data features selling in the event of any gain, and gentle buying all the way down to SPX 4000 in the event of losses (see the Chart Appendix PDF). This is a bearish pattern, but usually a stable one. So, all other things being equal, Tuesday has a mild bearish lean.
Robot Jim is still not on our team.
Jim's impression seems to be that not only do we [still] not have a directional edge, but nor do we have a volatility edge. He expects that the tails aren't really in play, anyway. It's not an exciting 1-week distribution.
As such, our bearish leanings and our end-of-month put options rely entirely on our own discretion. So let's wrap up this week talking about all our super-smart reasons for burning put premium over the past couple weeks, and continuing to do so.
Stupid to be Smarter
We
started the year by reiterating that bond underperformance in 2022 seemed to have given way to a discretionary decision to "replace" the long-equity ballast of a 60/40 portfolio (or similar) with 20-year Treasuries at 4.50%. So, a lot of people switched to a "40/60" portfolio. Sounds corny, but part of the evidence of this—aside from the bid in bonds—was that it coincided perfectly with a period of net SPX put sales and call-buying.
In other words, investors were no longer committed to long S&P (uninvested or under-invested as of 4Q2021), but loved the idea of participating in big upside (with long calls), and betting against a crash (with short puts)—turning their S&P exposure into a "long-carry, long-convexity" position. Thus, to blamelessly collect 4.50% yield (or >200bps higher on some suitable corporates) while having no "fear of missing out" in equities.
Now here's what's interesting: Imagine that 20-year Treasuries move back toward 4.50%:
- On the way there, equities don't get a bid, because the 40/60 portfolio is shrinking, and there's no S&P reallocation (in either options or underlying).
- If you actually get there, demand probably gets triggered—a big, deep bid—and stocks either get ignored, or sold to fund yield-seeking.
- Then, if all this goes on long enough, the SPX puts that were innocently sold (and still are) to achieve that cute positive-carry, positive-convexity payout become more and more in danger of being rolled down and out, triggering large negative SPX delta flows.
Point is—everything is pointing in the wrong direction. Sure, these are all conditionals, and maybe you get a sort of gentle disinflation taking over, and the long end of the yield curve remains real stable, and everything's fine and boring. But the fact remains that there isn't an equivalently bullish S&P conditional scenario to the one laid out above. Positions and flows are weak, susceptible.
Right now, our suspicions that people were overbetting on the "un-flation" narrative seem to have been proven legitimate, but that's only the first step toward any of the above occurring. So, it's a start.
But
also right now, there's a massive bid, visible in a historically unprecedented
DIX, printing
≥50% for
a whole month now. This, we did not expect, but it feels a lot like a dumb-money FOMO bid. Perhaps it would be instructive to compare this current situation to the other times in the last 18 months that DIX and NPD have "disagreed." Long story short: NPD ended up being "right."
If you want a bull market, you want put-buyers.
Our "Strategic Outlook" remains the same: Leaning bearish. Long puts.
Enjoy the short week!
The SqueezeMetrics Team