All the charts and data we refer to can be found on the Yacht Club page.
Hey everyone,
Let's talk about long tails, but let's keep it short.
- Orange crush, vega convexity
- Living in the momentum
- The folly of tails
Orange crush, vega convexity
Last weekend, we thought there'd probably be a vol crush on Wednesday, and that everyone would breathe a "collective sigh of relief" once the election was over. (Recall that we had been short SPX for several weeks before the election on the inverse of the same premise.)
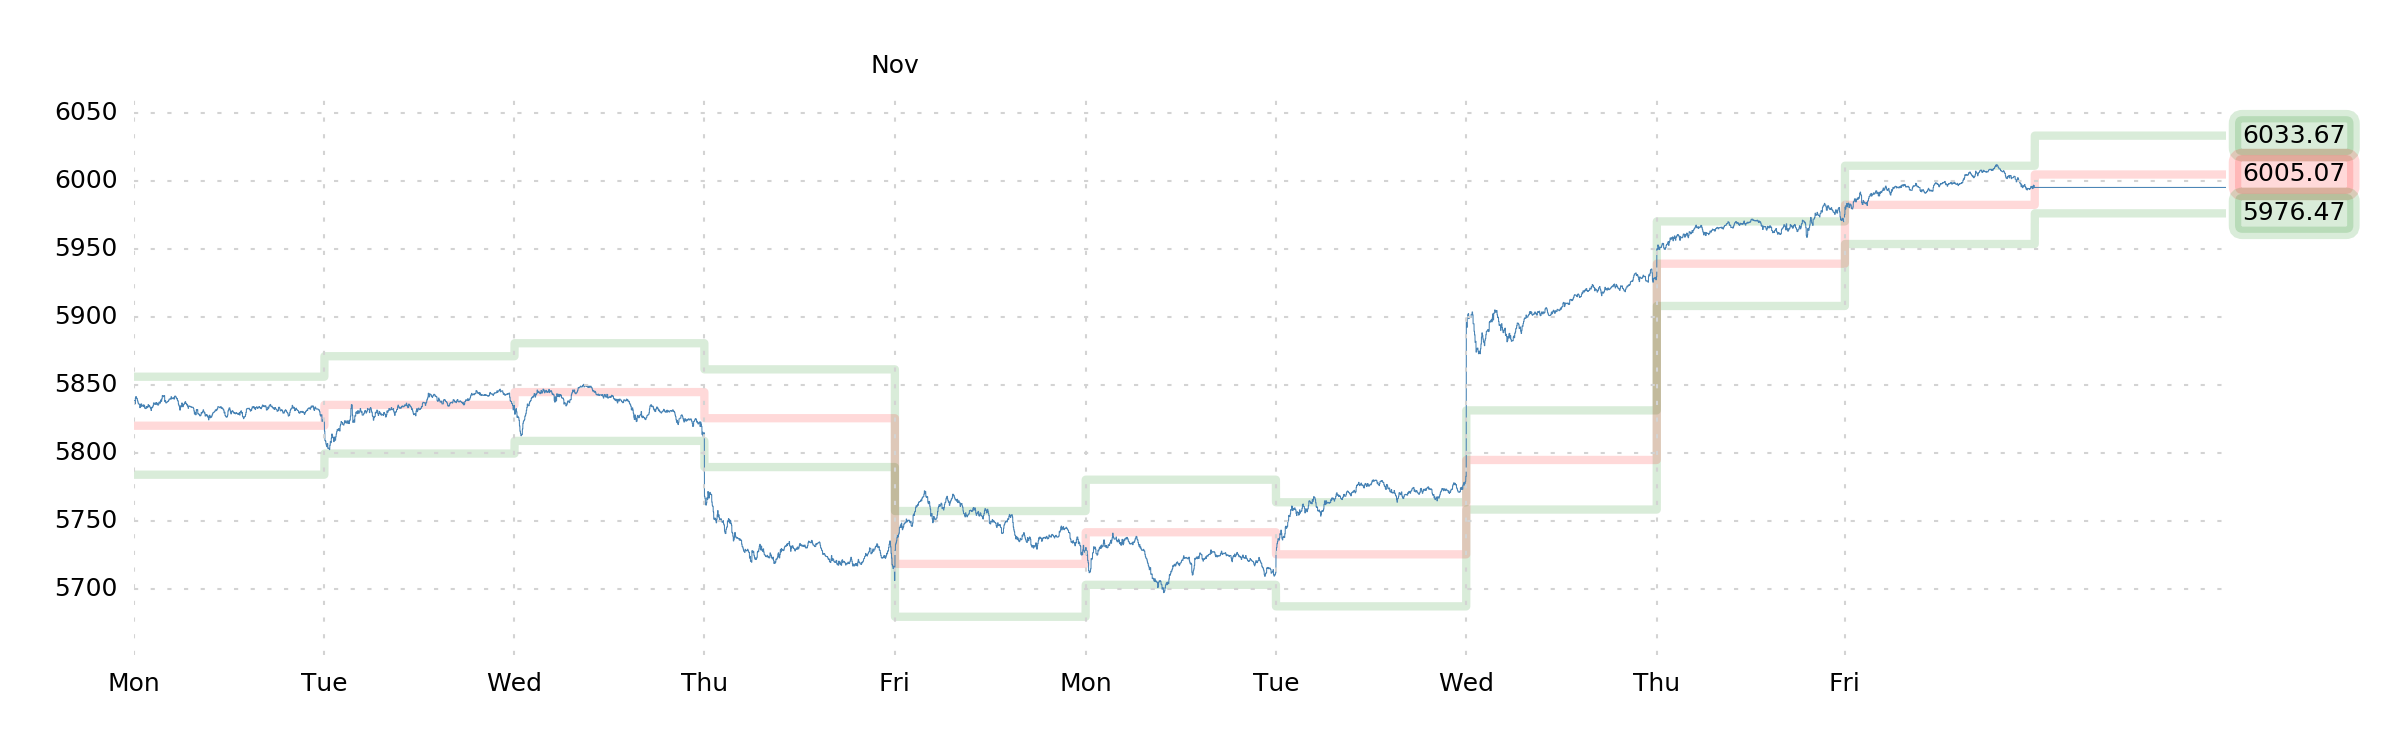
Indeed, there was a sigh. A great, heaving sigh. The S&P rocketed to 6000, and VIX closed the week with a 14 handle—the lowest it's been since August.
Anticipating this (the vol crush part, not the sheer extent of the SPX rally), we already knew we'd want to buy some cheap vega convexity, or volga, or vomma, or "left tail," or whatever you want to call it. And that's because we thought that the real risks of the election were less the election itself and more the consequences thereof—which could get pretty weird. So we bought 1-month far OTM puts on Thursday. We haven't done anything like that in a while.
(We also got short some bonds on Friday morning, but that's just because the flows and positioning looked lousy. Hopefully that resolves in our favor this coming week, as we aren't at all committed to a "bond short" as a long-term position.)
As a testament to just how strong the week's flows were, we thought we were being clever betting against the S&P price-action on Friday ("Short E-minis out of the gate"), but SPX still settled up 0.38%—much to our chagrin.
So we lost money this week, and as long as we plan on holding these puts, the plan is to keep losing a bit more, bit by bit.
Living in the momentum
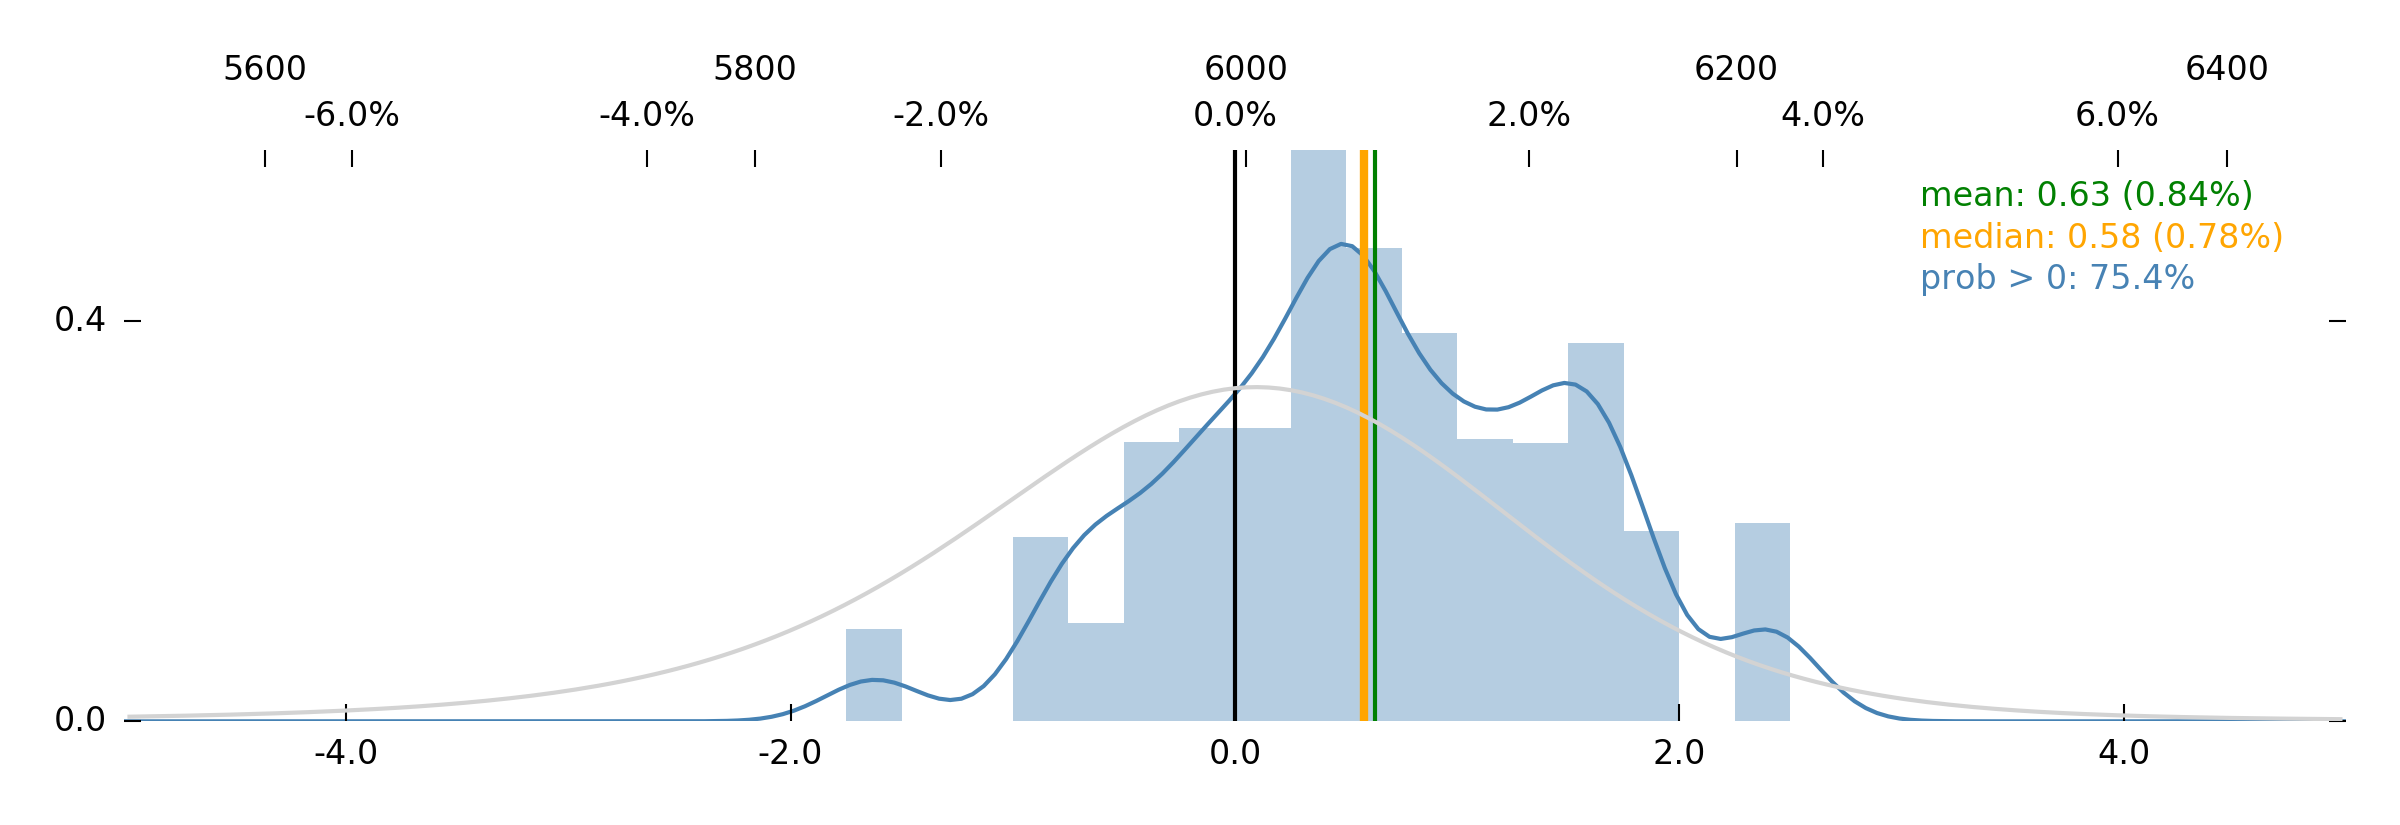
Despite the fact that Jim's current 1-week distribution no longer features that left tail, we won't forget that he had it there all of last week.
Granted, he also had a strong, bullish median expected return, and still does. Because the most likely outcome is further momentum.
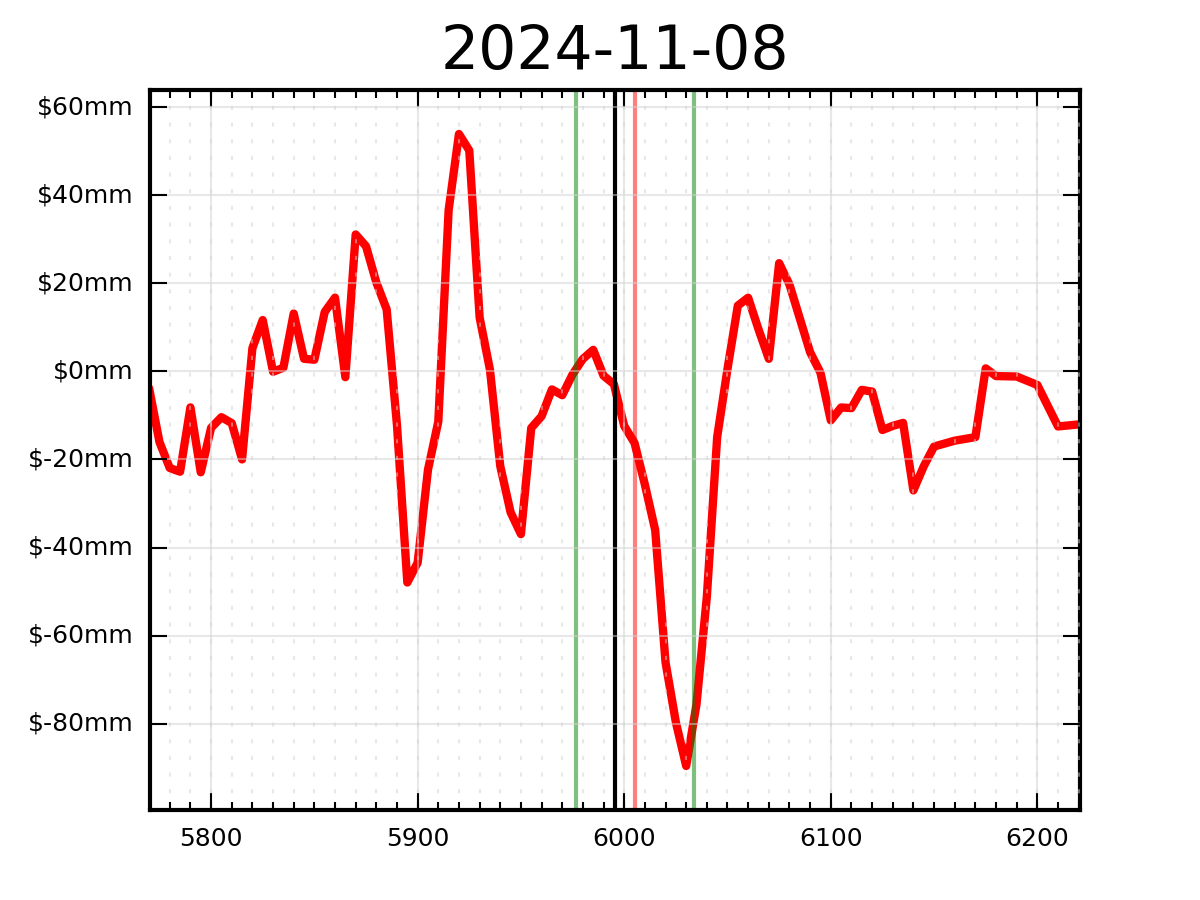
Where this gets more complex is that the 0DTE data relevant to Monday's trading is decidedly bearish. There's selling on the way up to the Monday Momentum band, and quite a lot of it.
How much post-election discretionary buying remains? Does the Trump Train, months before inauguration, still have some steam? Will we get run over again on an intraday E-mini short?
We're going to go into the week expecting that the highest-probability outcome is a bit of a breather on Monday, and then some resumed bullish-stable action. Regardless of what you think about the actual impact of Trumpy policies on stocks, it's hard to counter really strong momentum, frenzied buying, and fresh, high GEX.
(A call spread is probably the rational response to all this, really.)
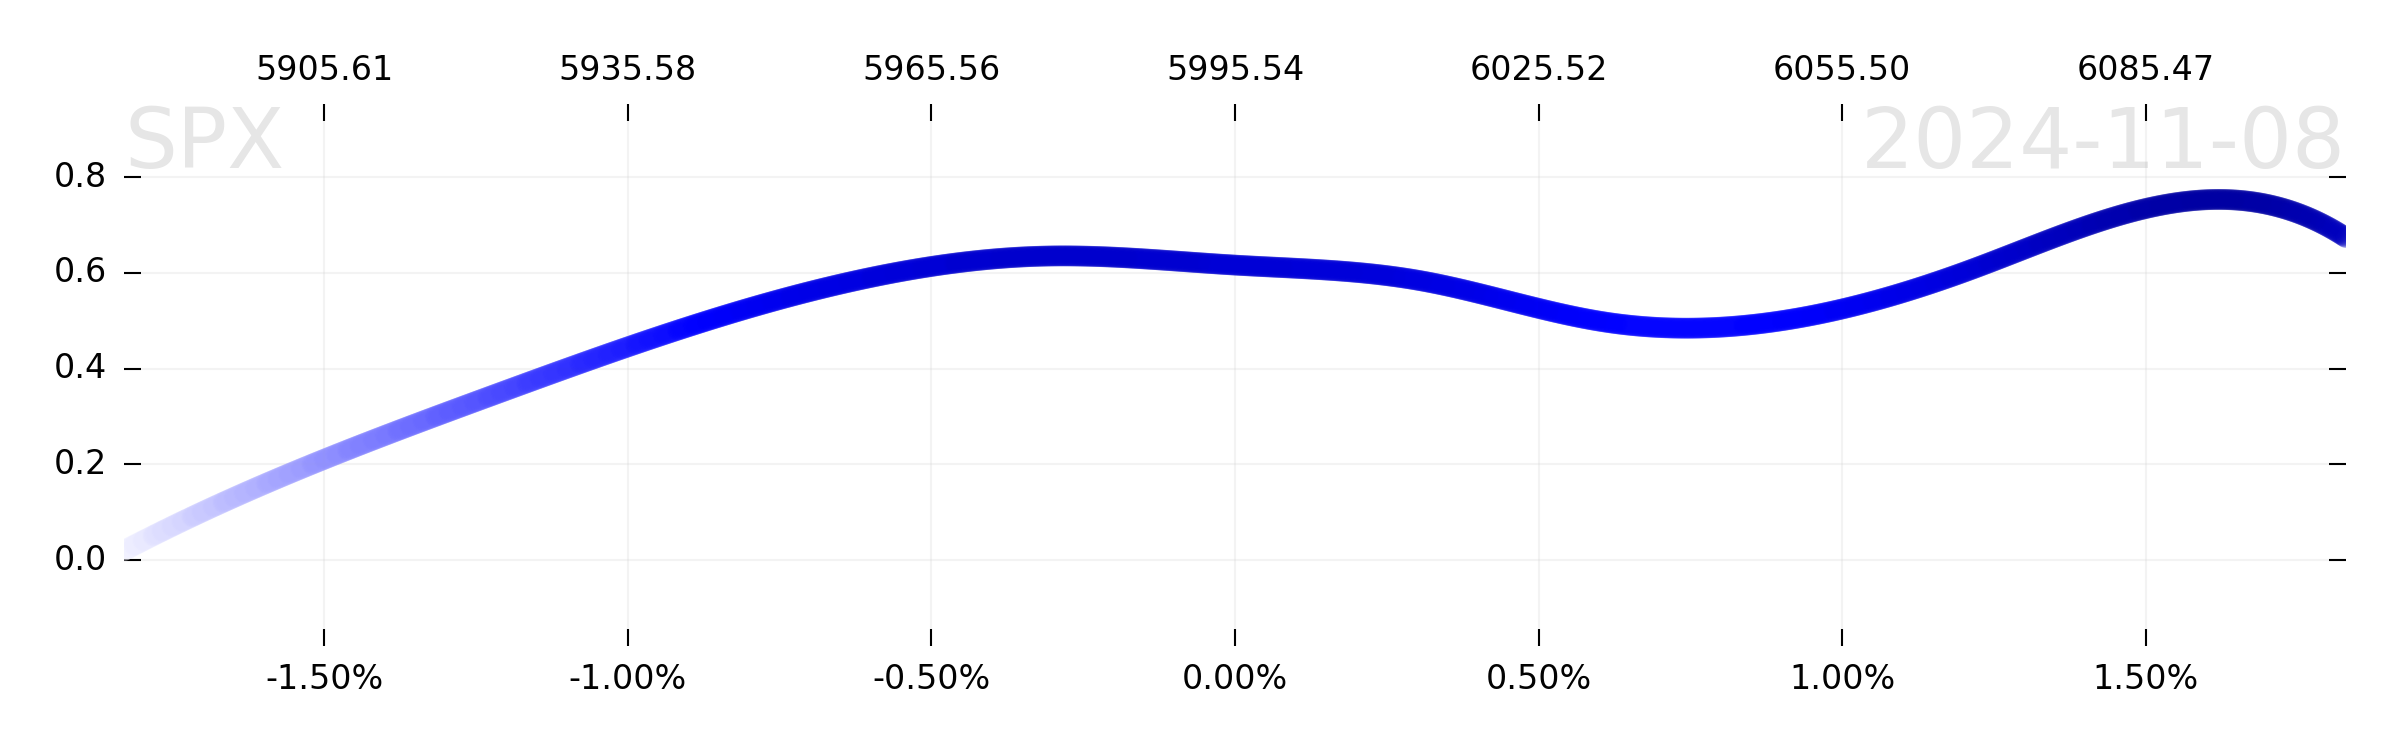
In keeping with this momentum, Robot Jim's step-forward tells us that forecasts are likely to stay strong.
So if just about everything (aside from Monday's 0DTE data) looks so peachy, why are we obsessing about the tail?
The folly of tails
You already know, dear reader, that there's little upside to buying tails. You have a 99% chance of losing money and getting laughed at, and in the 1% of cases where you do make money, people just think you got lucky at their expense and that you're a weird doomer jerk. And beyond all the social feel-badness, you had better monetize that tail bet at the right time, too, because if you don't, you get left with very little money even though you were "right." It's a garbage pastime.
As such, we are rarely long tails. The last time we remember buying tail puts was some time in 2022, on the off chance that some lousy positioning and flows ("dealer disintermediation") led to a crash. (It didn't.)
This time, we have no such excuse: We're all-in on the "weird doomer jerk" thing, because in our estimation, the next few months are even more geopolitically risky than before. Lest we forget: The president-elect has evaded several assassination attempts already, and this is only one flavor of "event risk." VIX could easily be above 14 right now on that concern alone.
We're trying, and struggling, to expand upon this—but all we can say is that we seem to be entering a new type of political and market environment, where a Trump victory just sort of gives "permission" for other things to start happening. Things that wanted to happen anyway, but were waiting in the wings. "Known unknowns."
Maybe we can turn this into a more coherent thought? Hmm...
It's something like this, actually: You know how "dealer disintermediation" in the market appears to be the proximate cause of volatility in so many cases? Because the intermediary, the dealer, becomes less active or less relevant due to the way customers are positioned (and because the dealer is the most predictable, orderly market participant, they're stabilizing to prices)?
We think of a Trump victory, and the attendant circumstances, as something similar to that. A "disintermediation." And now we feel like there will be some "gaps," and "vol-of-vol" occurring in the world. Because there's an opening for it, and whenever there's an opening for it, crazy stuff has to happen, as if by some natural law.
But we can, and we must, believe all of this without actually peddling doom. Because there will still be long walks, and fireside tonics, and there will still be spring, and blooms, and veranda weather, and the sound of ice in a glass. And the market will still probably go up all the while. But despite all that, it's still a good time to own some deep OTM puts.
Enjoy the week!
The SqueezeMetrics Team