All the charts and data we refer to can be found on the Yacht Club page.
Hey everyone,
It is mid-September. A chill is in the air.
The flow of information has been odd lately. We've spoken of "limbo" and "uncertainty," but we've also used every opportunity to insist that "it's a bear market, you know." Which is all to say, again, that we think buying stocks here is not a good idea per se. Flows are constrained, or "muted," and there is neither much money nor much will to take that extra punt on stocks. Like we said last weekend:
And ultimately, that seems to mean fresh boredom. Those familiar bull-market patterns are gone. Flows are muted. There are neither net put-buyers nor sellers, save for in the nearest tenors, and the impact of that positioning is in day-to-day wiggles, not month-to-month trends.
We've
brought up Erwin Schrödinger before, on a similar subject, and this quote comes to mind once again:
There is a difference between a shaky or out-of-focus photograph and a snapshot of clouds and fog banks.
We aspire, always, to secure the latter—to have a clear view of uncertainty, and an appreciation for the superiority of crisp, probabilistic thinking (however maddening that uncertainty can be). And yet, sometimes, we just don't feel like we have that crisp snapshot. Sometimes, like right now, we just feel like our prognostication is indeed muddy, shaky, out-of-focus, and necessarily so.
So, fair warning—that's pretty much what's going on in this note.
Let's try to "reason" our way through some things: Our Big-Picture view, our Strategic thought, our Holistic, Gigabrain Macro Thesis for 2023, has basically been that stocks will do poorly when bonds do poorly. Reason being: People bought bonds and took FOMO punts (calls, risk-reversals) on SPX, with no intention of actually being linear "long equities" in a normal way. So, the better bonds perform (capital-gain-wise), the more gravy drips into stocks. Capital losses, of course, mean no gravy for stocks.
The other Gigabrain Macro thought, the companion to the above, was that the marginal price-setters of the rates market (price-takers, leveraged and otherwise) seem to have bet pretty big on disinflation (directly or indirectly), and after a decade or so of, e.g., a sub-3.00% 10-year note, were extra-willing to take the yield, when offered. Thus, bond returns were more likely to languish, with eager bets already having been placed on price recovery (or, for the economics-minded, with "demand having been pulled forward").
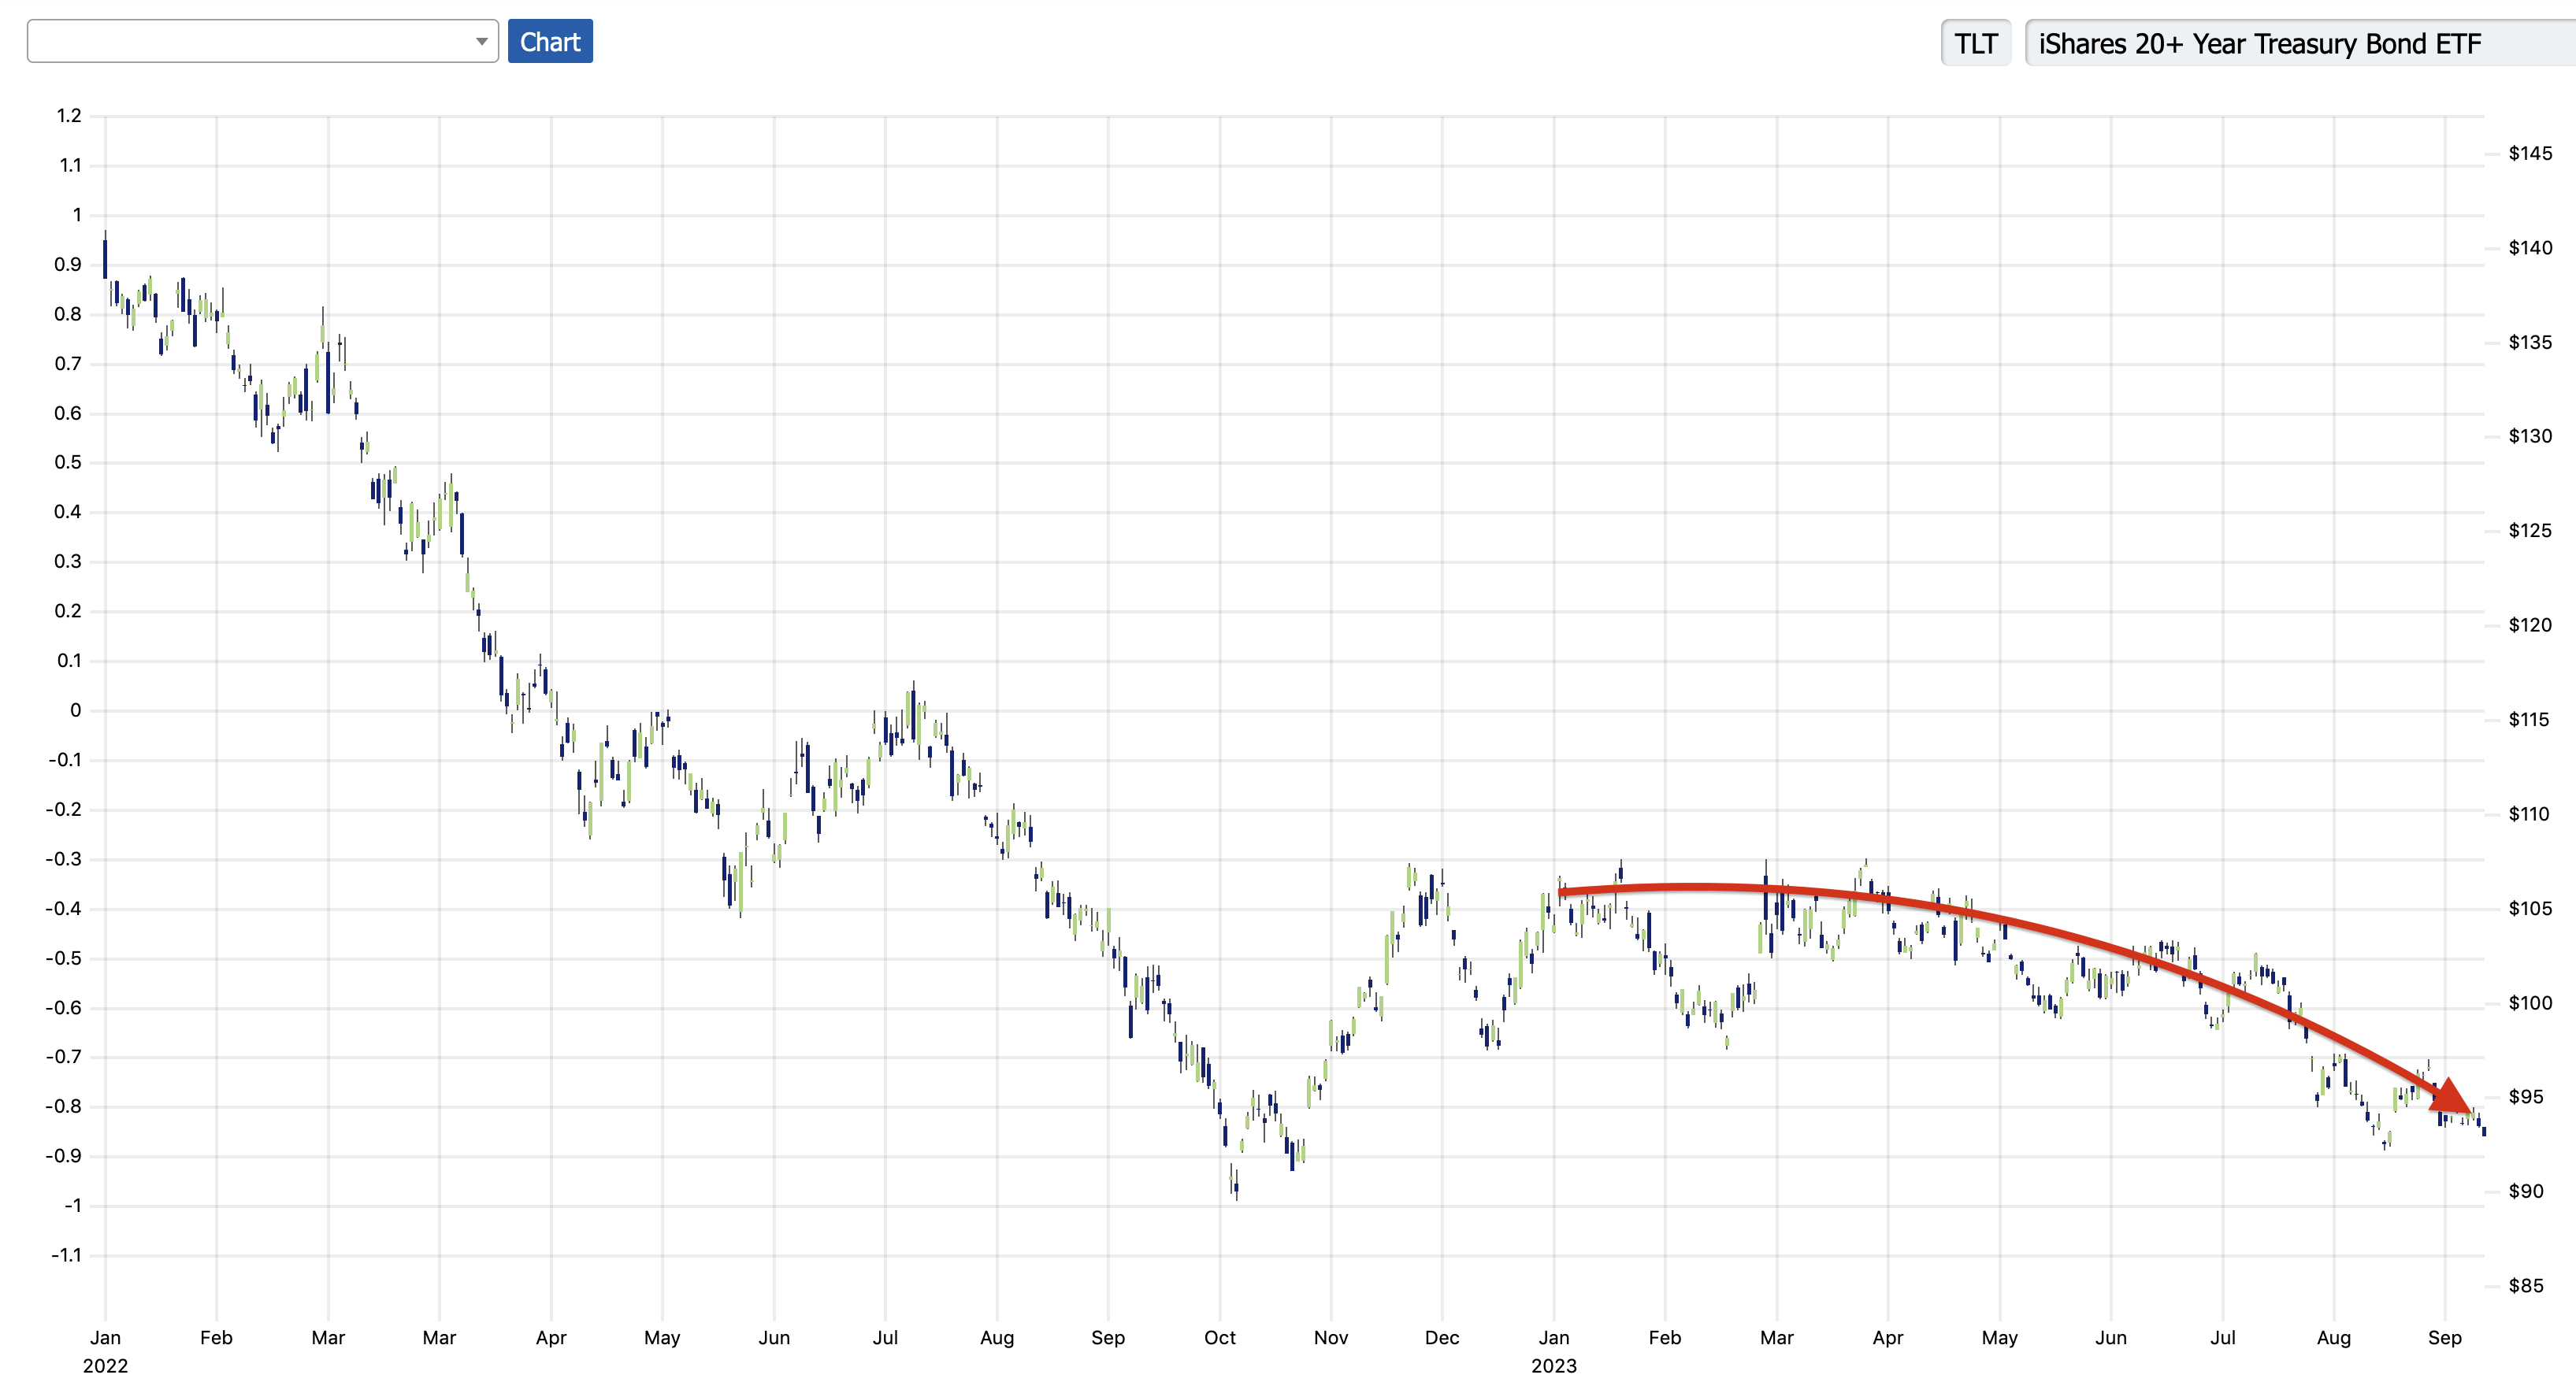
Thus, this droopy chart of TLT (which is a chart of total return of a long-term bond portfolio with slightly weird convexity characteristics) is pretty much what we expected to see—a natural path for the above situation.
And really, all other things being equal, we'd expect to see it take a quick jog lower (based on the nature of the supposed positioning). Which is probably not a good thing for stocks (because of the gravy).
It's a bear market, you know.
But consider the alternative! Consider that fears of recession re-emerge (remember the banking crisis a couple months ago?). That might be good for bonds, but it's also probably not going to be good for stocks (because recession). Indeed, it seems like the only good thing for stocks would be bonds going gently, calmly, up.
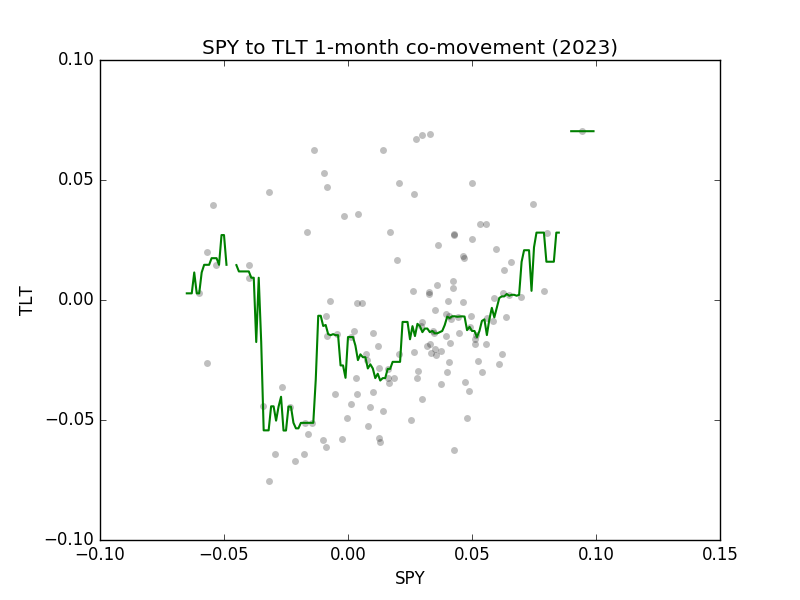
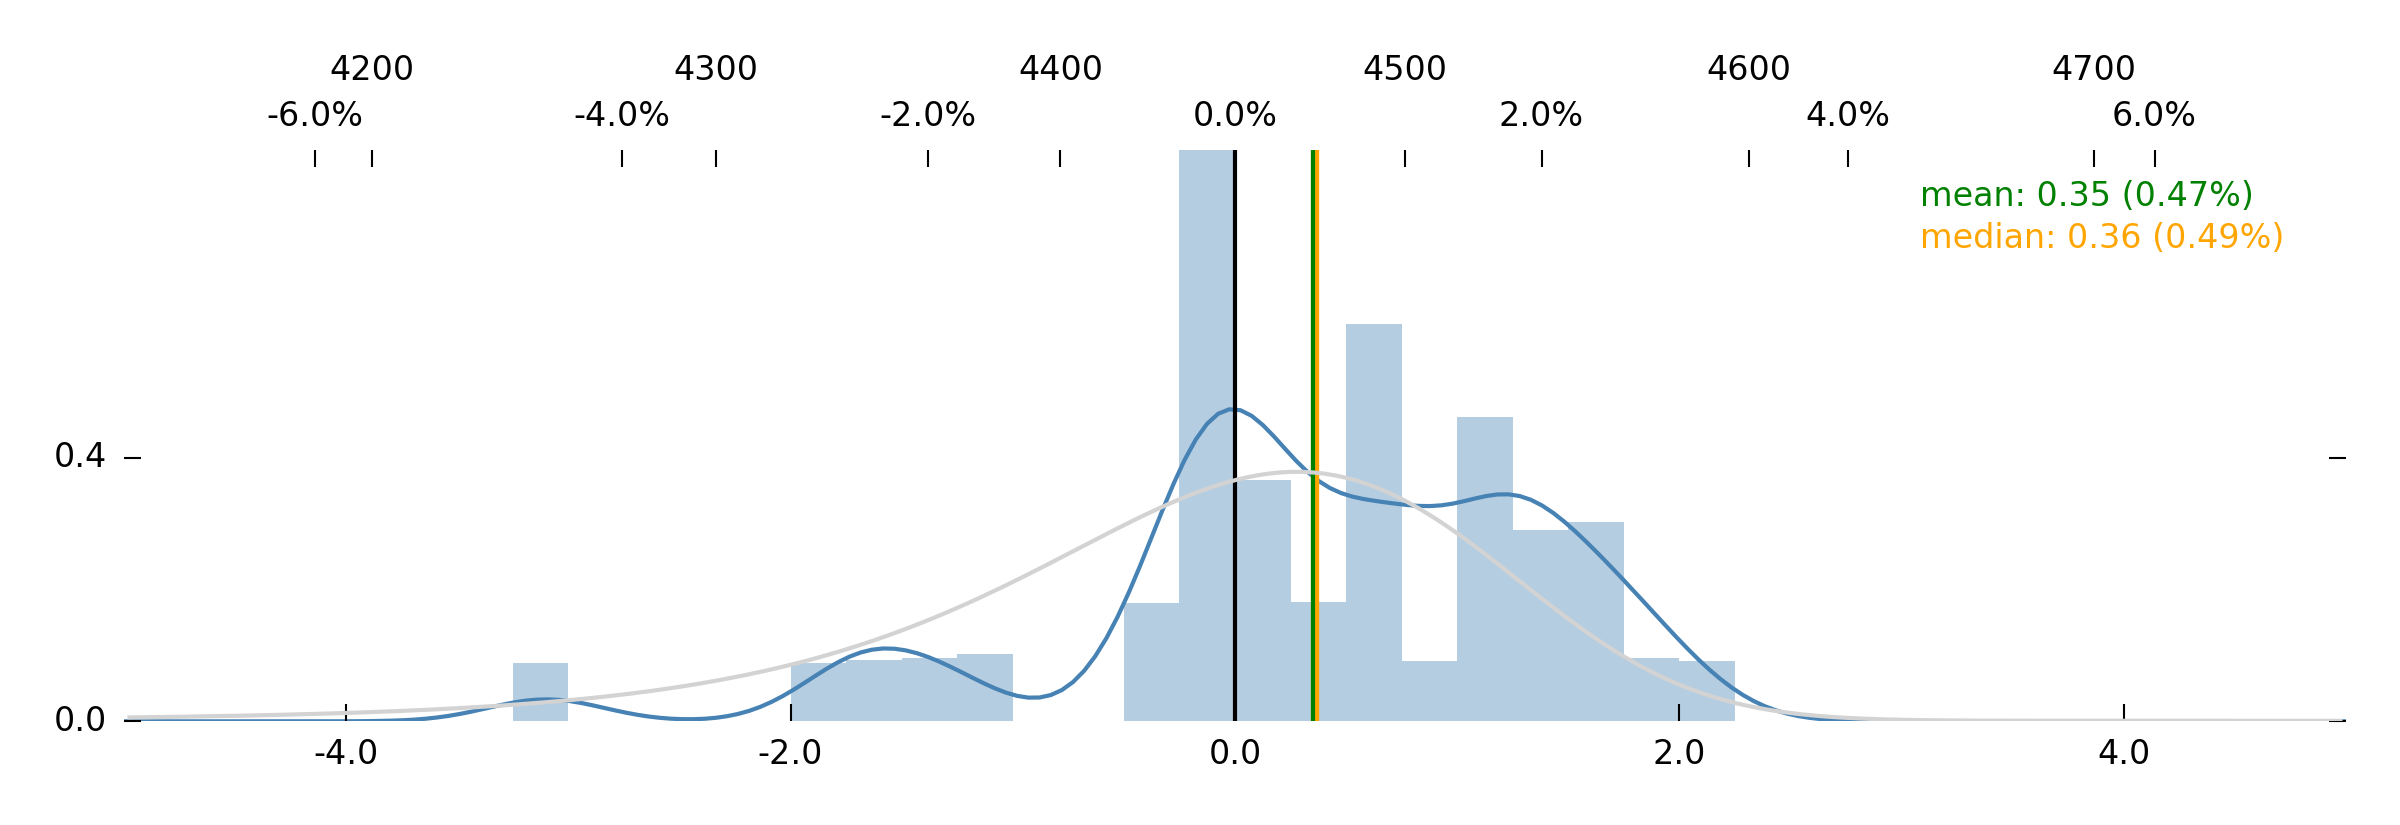
This rather bearish condundrum is clarified in the context of the 1-month co-movement of SPY and TLT observed in 2023 so far. Out there to the far left, you see "recession fear," where SPY was down by TLT was flat to up; but otherwise you see a strong positive correlation, driven by the Big-Picture stuff above.
No, none of what we're saying is new. Even at the very beginning of 2023 (and before), we were saying the same thing (though we didn't think SPX would manage to log such strong returns as bonds languished like this—even if you justify stocks as "an inflation hedge").
The only thing that's new, right now, is that instead of saying "expect more boring-ness" and "oh, it looks like there's some support here" like we have been since April or whatever—we feel like a bit of inevitable volatility is actually drawing near. Again, this is all muddy, shaky, and out-of-focus, but it feels like there's actually some room to move.
Consider, for instance, probably the most noteworthy data from this past week—and definitely the most noteworthy thing that's happened in GEX+ in a long time.
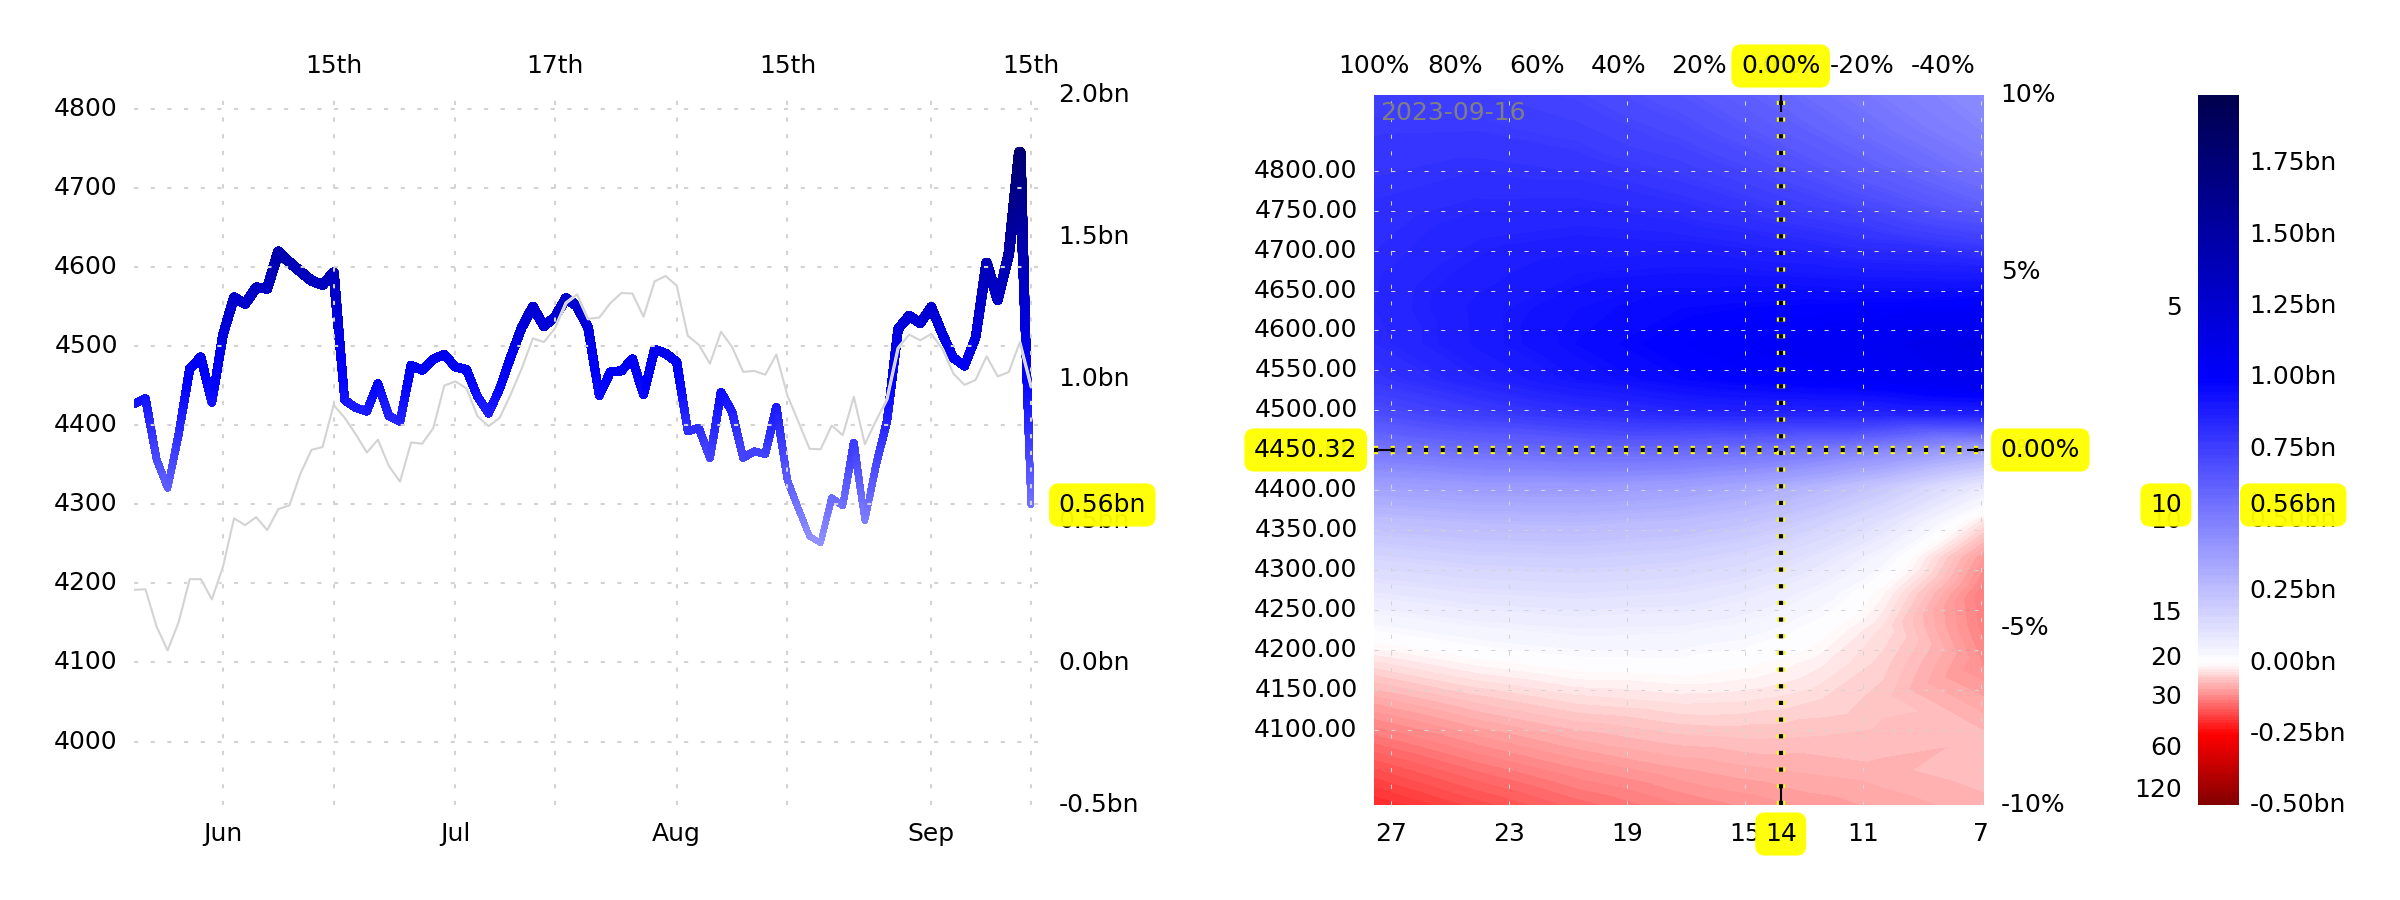
GEX+ fell from some $1.8bn all the way to $0.56bn after the expiration of the monthly SPXAM and the Weekly Friday SPXW. In isolation, this doesn't tell us anything about market direction (we just spent 30 minutes making sure we could confidently say that, by the way), but it does tell us a lot about potential for movement. Gamma-implied vol (GIV) rose, in kind, from 4 to 10 (0.20% to 0.50% expected average daily moves). That's a lot more wiggle potential.
Now think about FOMC on Wednesday, which has been mostly uninteresting lately, but which has plenty of opportunity here to surprise (Powell could say any number of things to spur on some worry), especially with VIX at 13, implying very little term risk premium in excess of the baked-in gamma/variance risk premium. And are we allowed to say that maybe, just maybe, a short VIX PnL has been a bit too good over the past month? We haven't been long vega in forever, and we haven't been keen to be, but you could choose a much worse time.
What about energy prices? What about that banking crisis that was mostly forgotten but never fully resolved? What about the looming Treasury issuance, government shutdown, and the budget needs of populist politicking? What about consumer spending running up against headwinds, and Federal student loan payments restarting soon?
We don't usually talk about conventional "bearish" things, "recessionary" things, "economic" things. We just bring it up when we start to hear genuine concern from actually-smart people. And it's there. For the first time in a while, we hear not-permabears talking about an accumulation of headwinds—lots of little things.
Of course, we don't want to be unduly influenced by such whispers. We just want to make the right trade. And, as a counterpoint to the breathless bear-porn above, we actually thought that the right trade on this past Friday at 3:30pm was to buy a next-Friday SPX call option, after sitting on our hands all week (a week that ended flat).
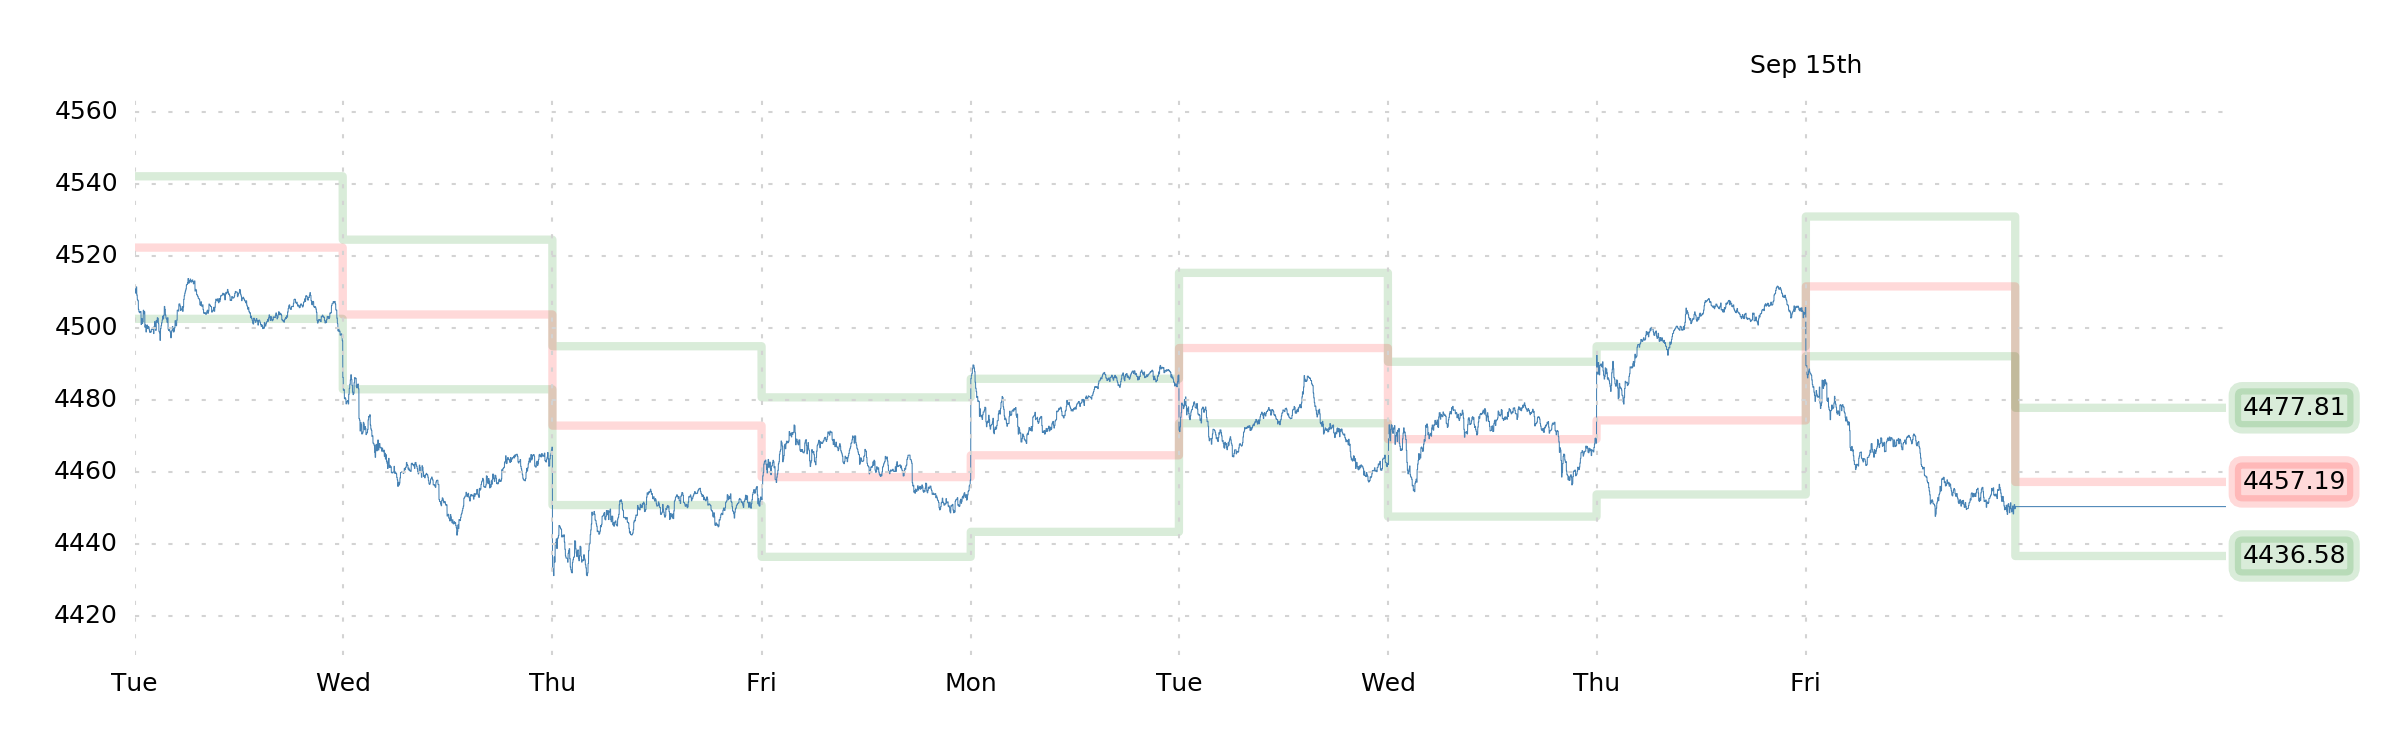
Largely, we were influenced by Robot Jim, whose distribution has been advertising stable-to-bullish returns since Monday (and it's all Jim who saved us from betting against that rally from April to August, so we owe him some consideration for that).
Partly, we are also influenced by our surprise at the intensity of the Friday selloff. It seems likely that the selling was discretionary, informed significantly by the decrease in dealer gamma in the morning (and thus, the decrease in top-of-book SPX liquidity). But in light of the true liquidity situation (not that bad), we thought it seemed overdone. A bet on a substantial reversion seemed smart. And it's a cheap bet.
At the same time, we have not felt this actually-bearish in an awful long time. Despite feeling that there is no crash risk, we feel like most paths lead to "stocks down," for real.
So now, as long as we're dredging up old quotes, let's reproduce another one,
from August, that we self-consciously lifted from Nathaniel Hawthorne:
"It is remarkable, that persons who speculate the most boldly often conform with the most perfect quietude to the external regulations of society. The thoughts alone suffice them, without investing itself in the flesh and blood of action."
It's a bear market, you know; but right now, that thought alone does not suffice.
We're going to grab some linear short SPX exposure. Not sure how, yet, and it doesn't much matter—but we'd be happy to lose a bit of money being wrong for a couple weeks, or even months, while sitting on a short index position.
Is any of this convincing? Is this a scientific treatise, with unimpeachable premises and a pristine syllogistic conclusion? No and no—this is hearsay and gut-feeling, brought to us by muddy reasoning. But that's all we've got right now. And sometimes, you gotta work with what you've got.
Currently long a Friday call. Accumulating short SPX very soon. Finally expecting things to get more interesting. Hoping to stop saying "boring" in the morning notes. Starting to wear sweaters on the veranda.
***
Obviously, we got lost in the sauce today, so we neglected to follow up on last weekend's reseach, which was actually really exciting and fun. We're really curious to learn if RISC-VIBE has "worked" in 2022/3, so we're going to try backtesting that and pondering why and how something like RISC and/or VIBE works.
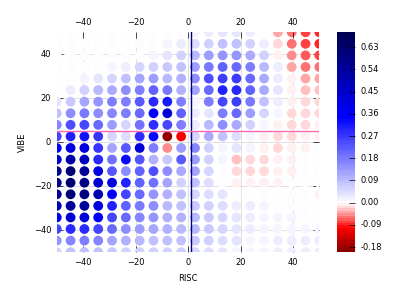
For the curious, here we are right now w/r/t RISC-VIBE.
Both are pretty close to zero. RISC falling a bit below zero would "trigger" the evil red zone. For RISC to fall below zero, you'd want options to catch a bit of a bid, and/or for the S&P to spend a couple more days moving very little, realizing very little volatility. That often occurs in the days ahead of FOMC. We'll see.
Alright, that's enough for today.
Enjoy the week!
The SqueezeMetrics Team